Shop lots in Taman Ungku Tun Aminah, Johor Bahru
Fifty-one recorded transactions — the second-highest turnover in Johor Bahru. A dense, high-footfall, low-ticket mass-market strip built on hawker food, gold shops and pharmacies.
- Ground floor rent
- RM2,500–6,300per month
- Median transacted
- RM1,120,000RM741 psf · 51 deals
- Peak trading
- Daily, seven days; morning and evening peaks
- Catchment
- Mass-market Chinese and Malay working households
The map loads here on the published site.
If you have never been here
The 60-second orientation.
- Zone
- Skudai, western Johor Bahru
- Main commercial street
- Jalan Pahlawan
- Transaction window
- June 2024 – May 2025
| Destination | Drive | Why it matters to a tenant |
|---|---|---|
| Skudai town | 5 min | Adjacent trade and services strip. |
| Sutera Utama | 8 min | The affluent alternative ten times the price. |
| Taman Universiti | 6 min | Student strip; overlapping price point. |
| Tuas Second Link | 25 min | Negligible Singaporean traffic. |
| JB City Centre / RTS | 25 min | No direct RTS benefit. |
Why this strip is busy
The demand engines — and what each one actually pays for.
Fifty-one transactions a year
The second-deepest turnover in Johor Bahru. For an agent, that is the business.
Genuine daily footfall
TUTA trades on volume, not occasion. Hawker stalls, gold shops and pharmacies pull people in every day of the week.
A near-even Chinese and Malay split
Both a hawker economy and a halal economy work here. That widens your addressable market considerably.
Low rent relative to footfall
Ground floors from RM2,500. Very few Johor strips give you this much traffic at this price.
What TUTA actually looks like
Real, freely-licensed photographs of this area — with the licence on every caption.
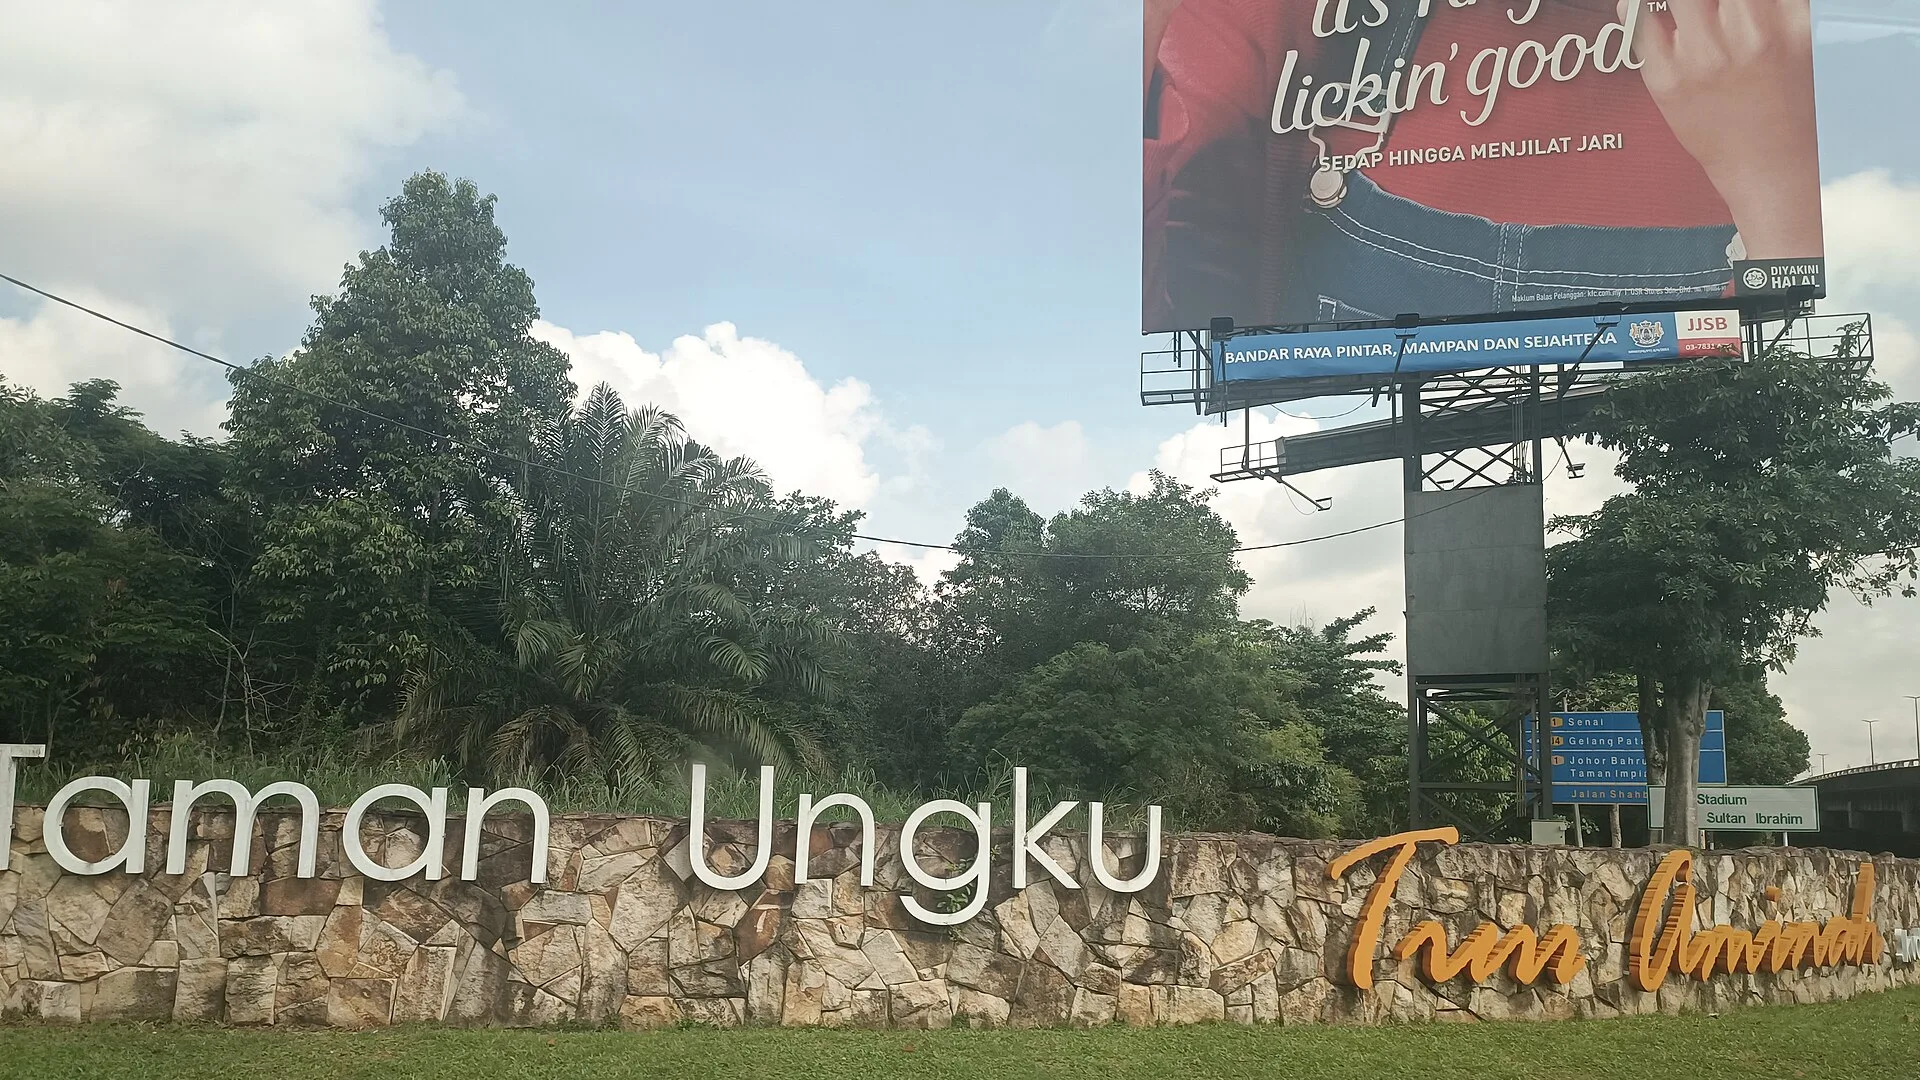
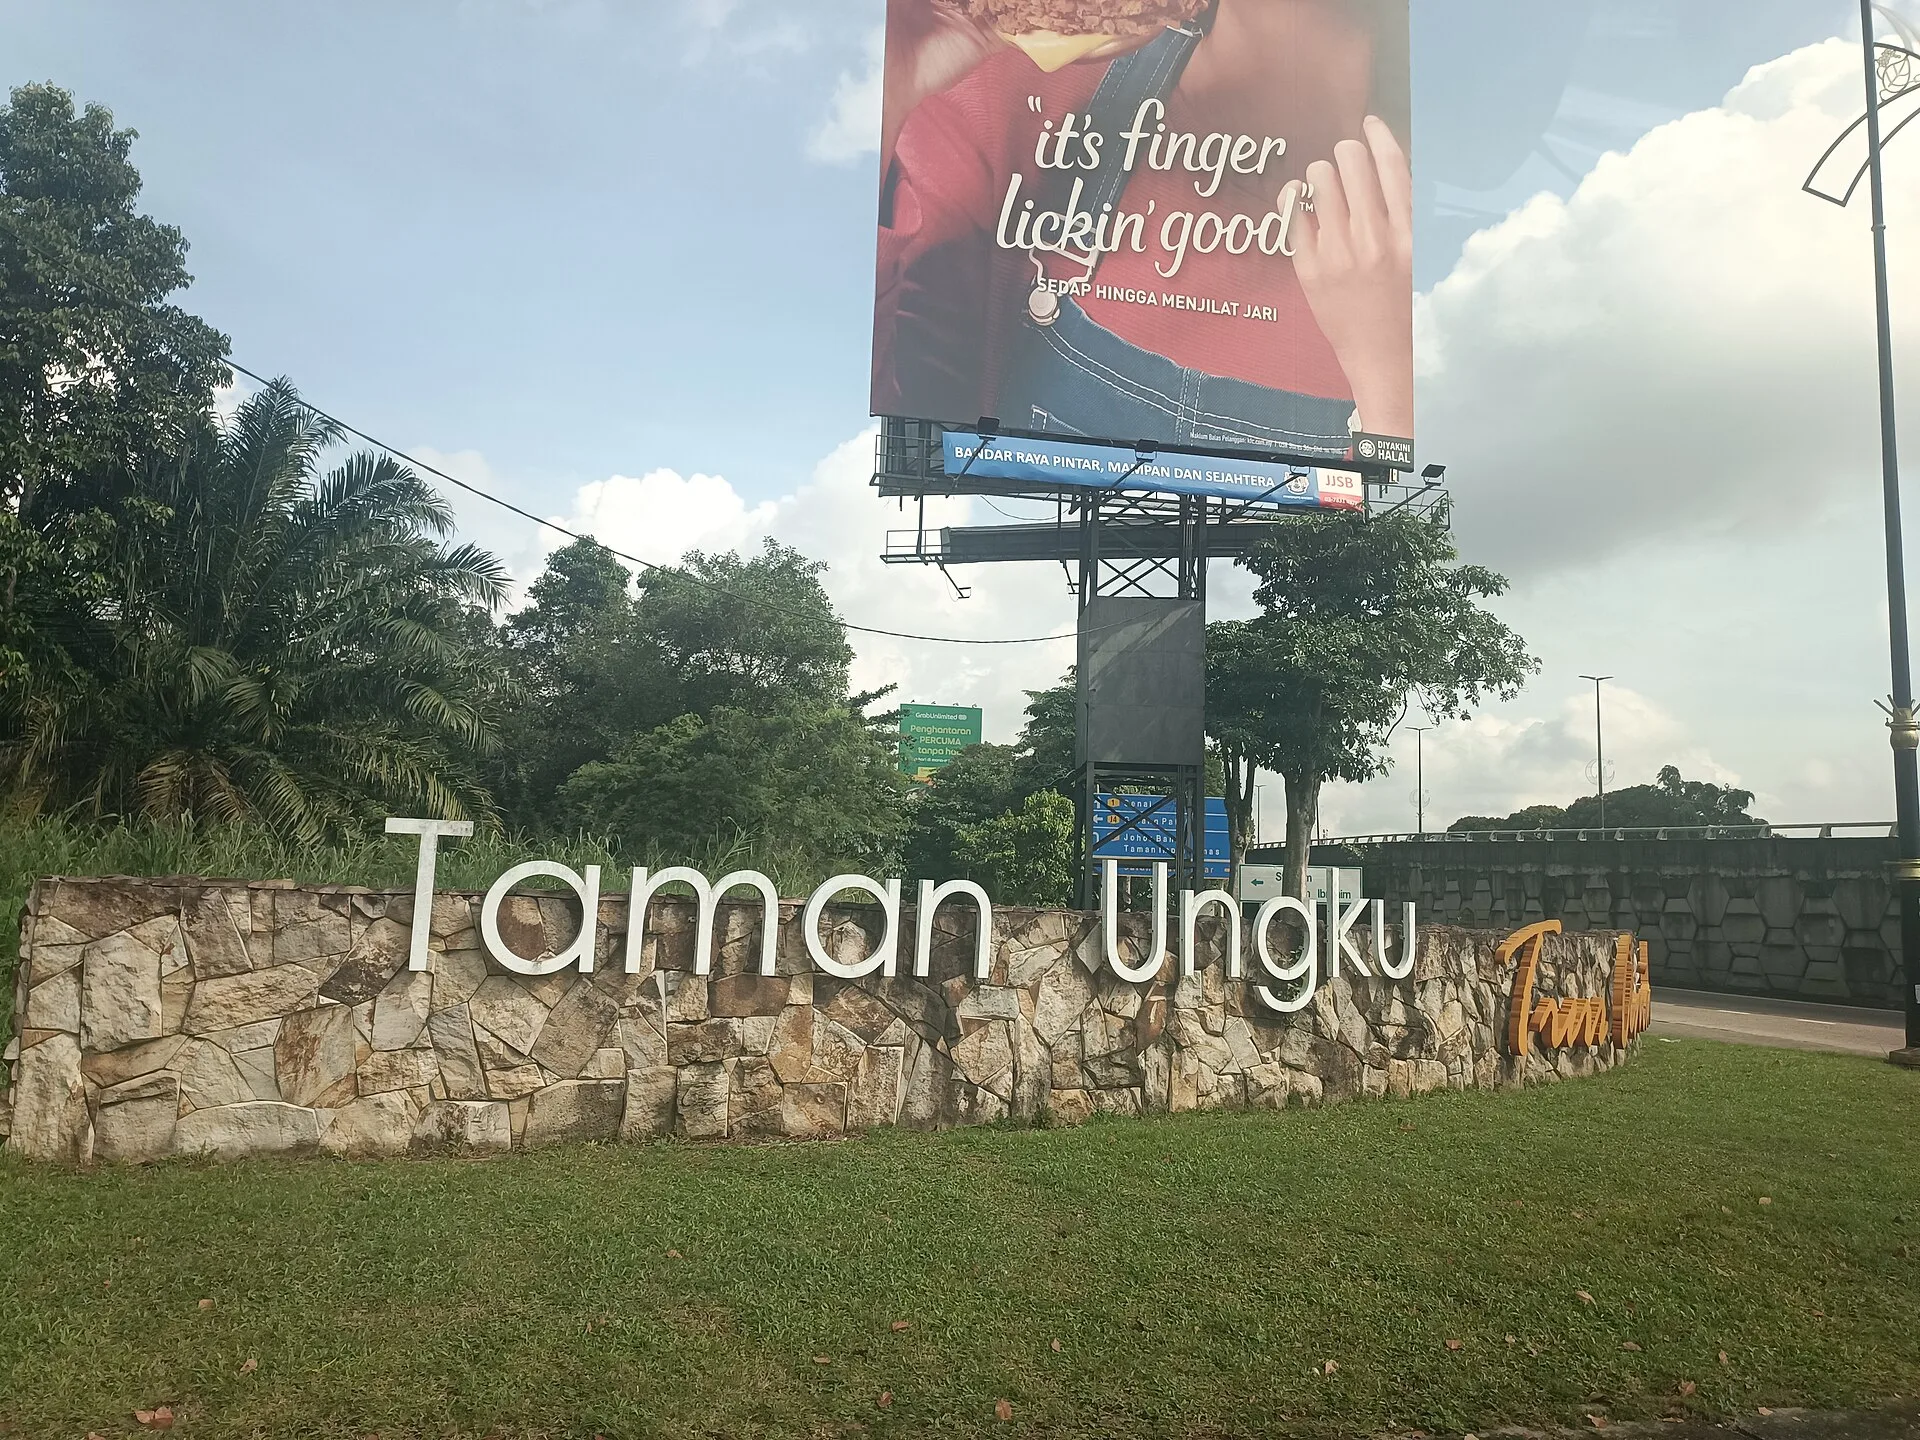
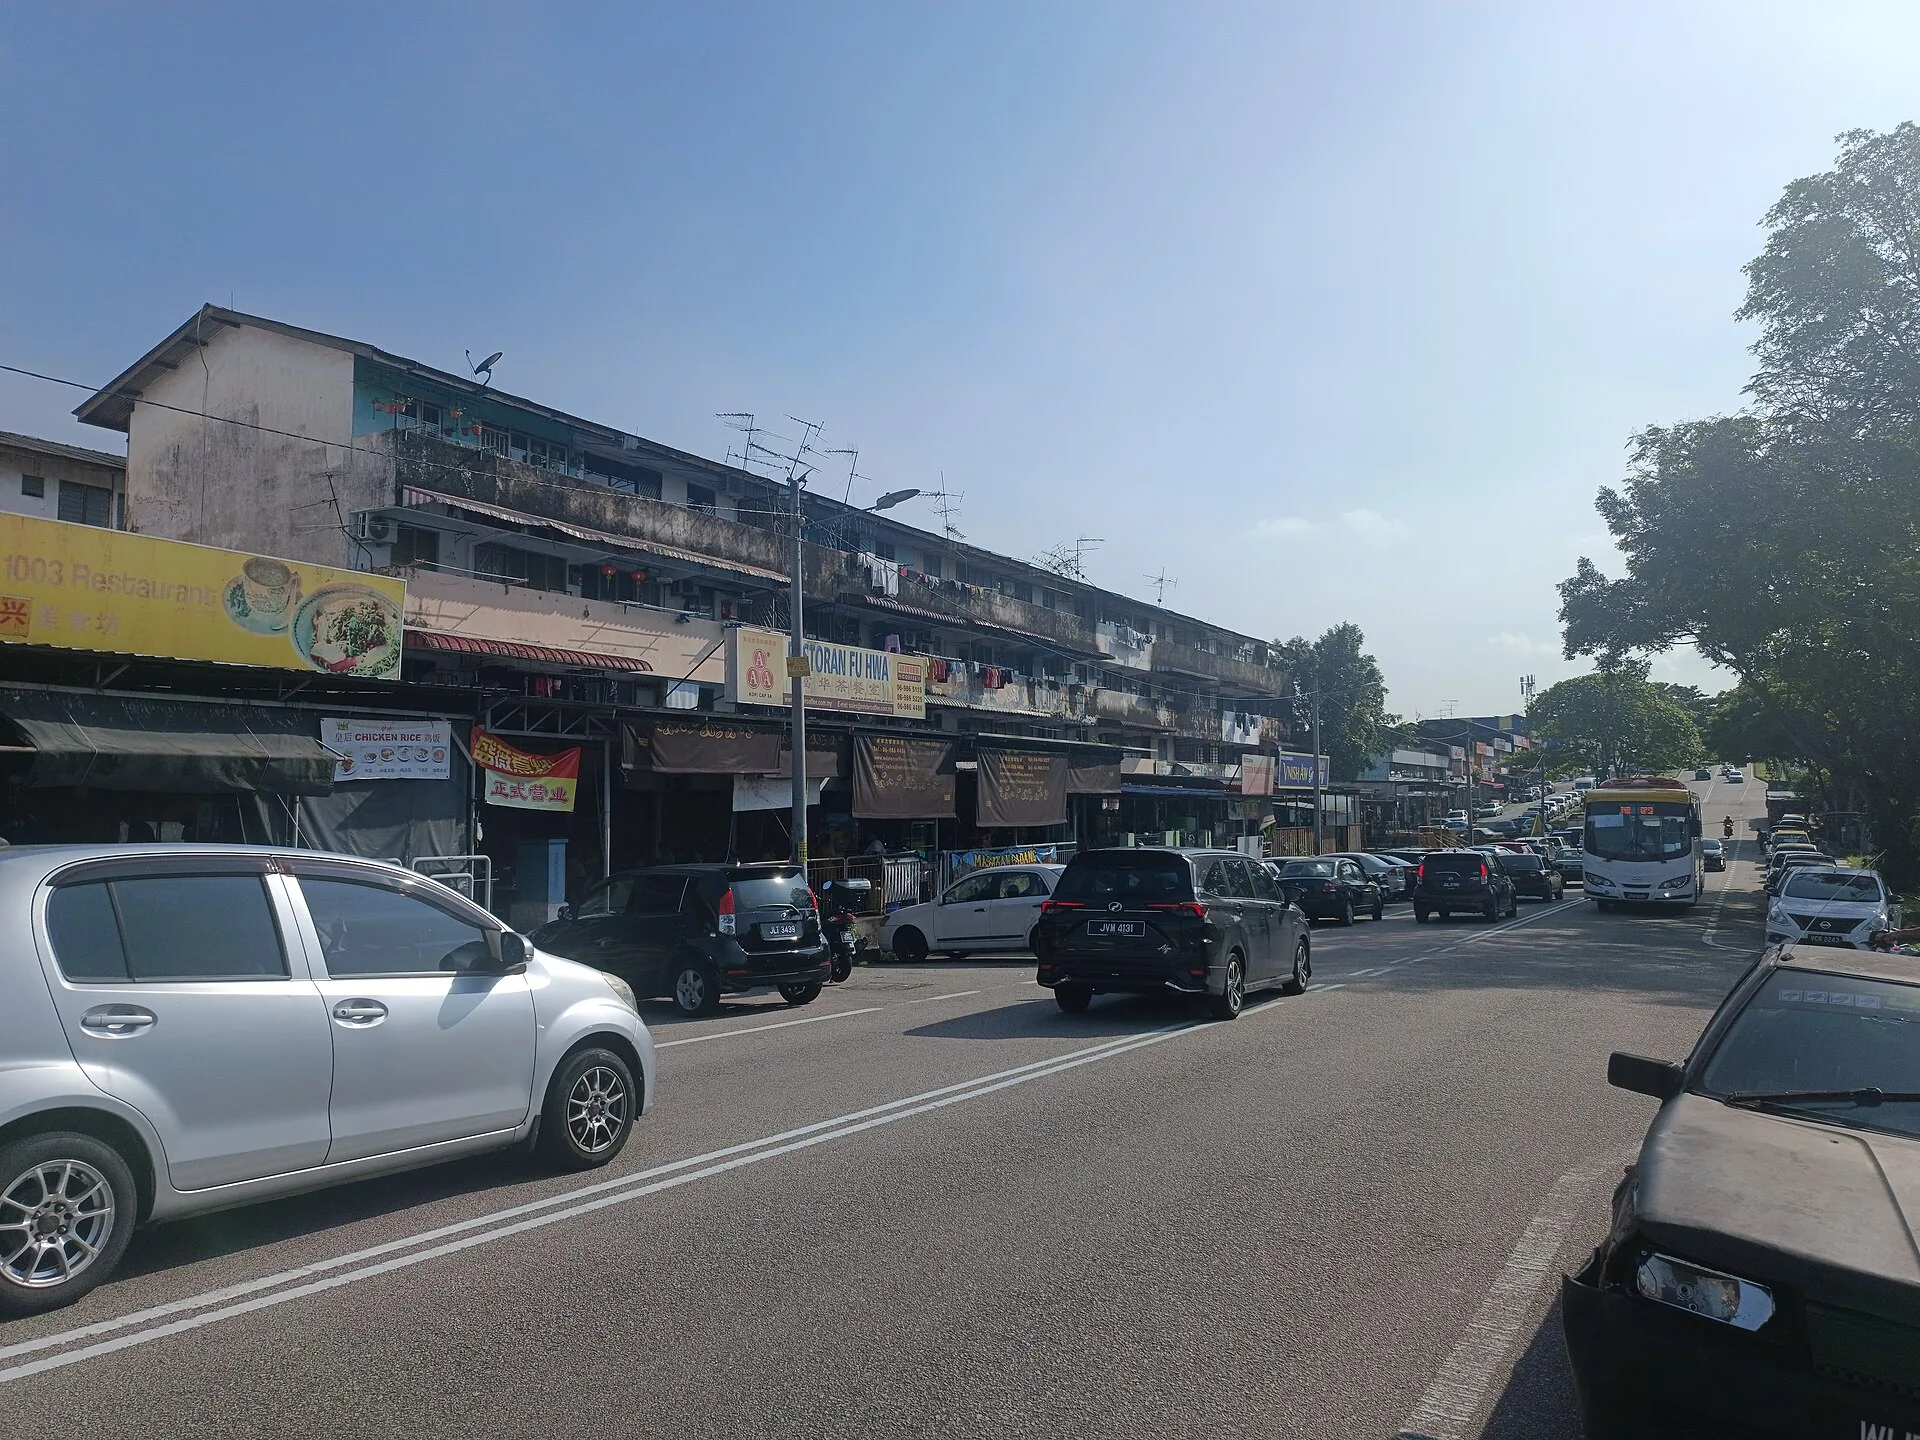
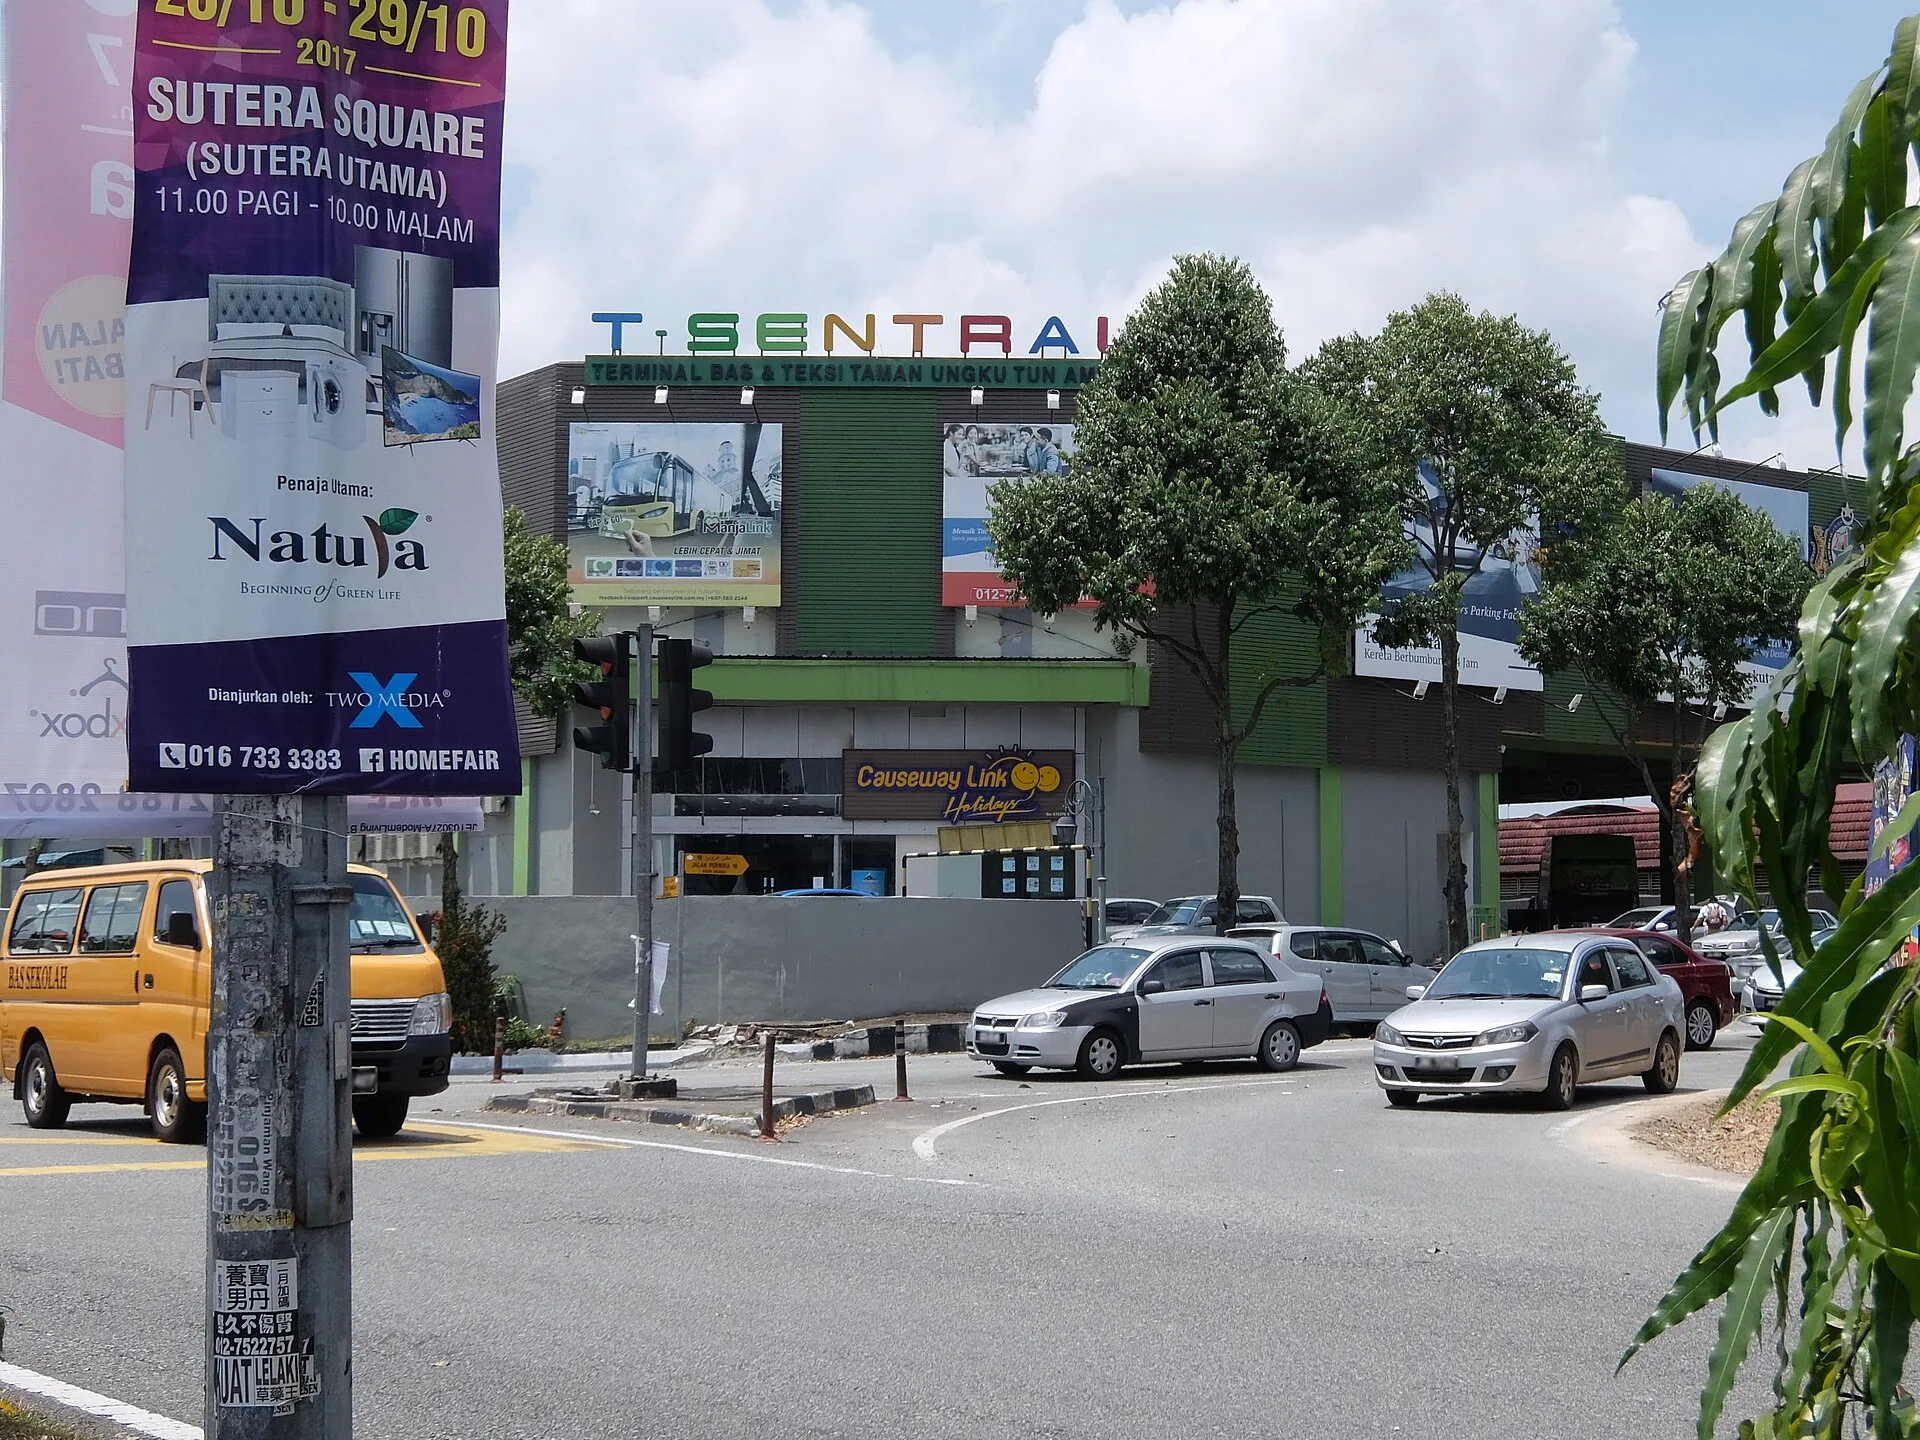
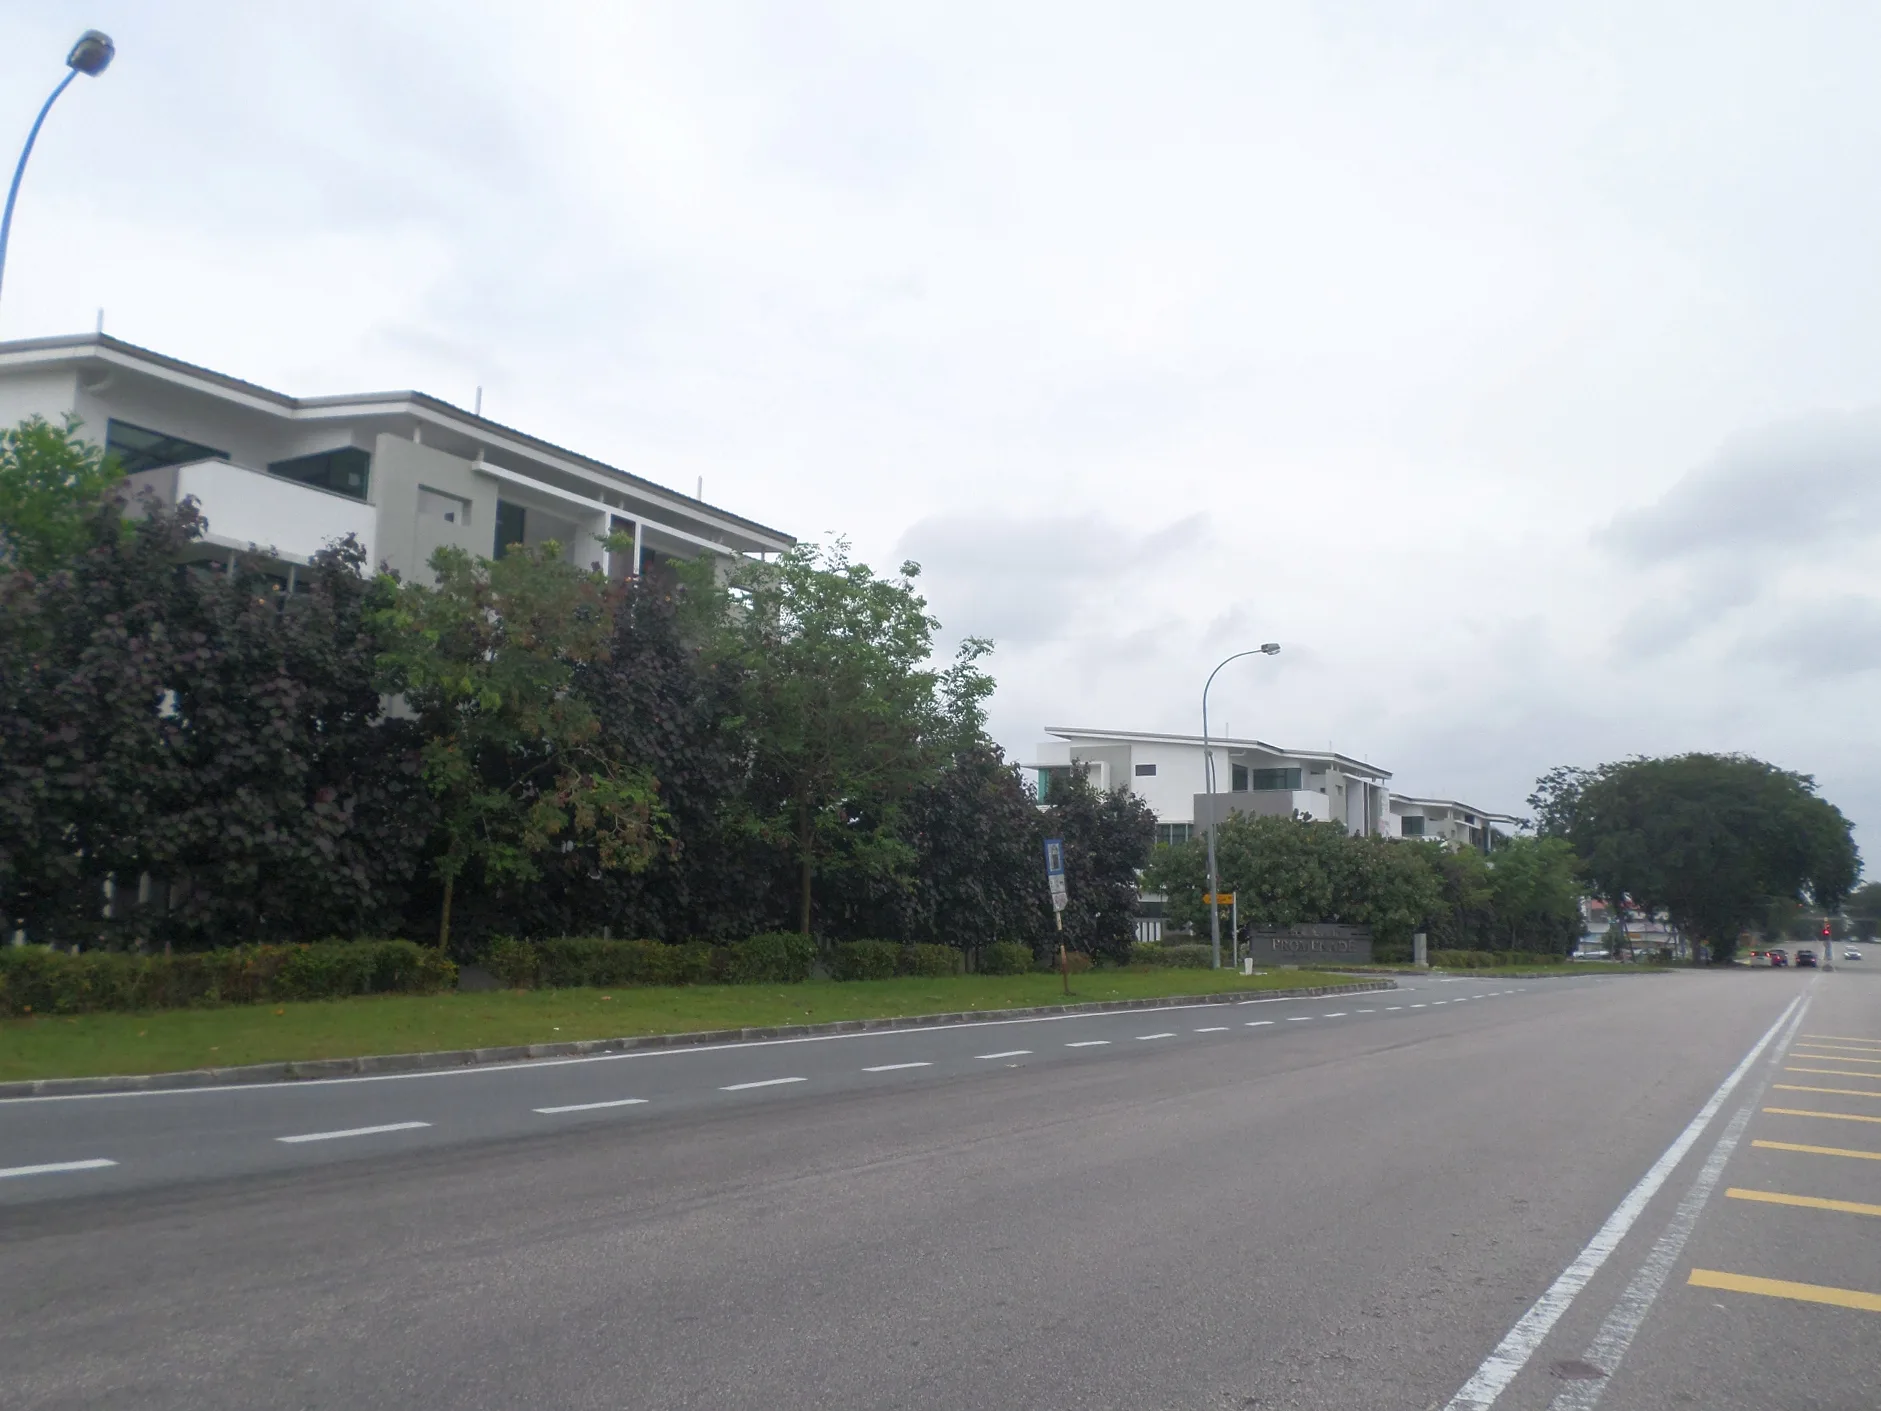
Every photograph on this page is a real, freely-licensed image of this area, reused with attribution under its stated Creative Commons licence — not a stock photo and not generated. Licences are linked on each caption. If you own a better shot of your own shopfront here, send it to us and we will feature it with a credit and a link.
What TUTA has that the others do not
Not “advantages” — structural facts a competing location cannot copy.
The second-highest transaction volume in JB
Fifty-one recorded deals. Liquidity at this level means you can both enter and exit.
Heritage retail that cannot be rebuilt
Gold shops, traditional pharmacies and hawker stalls with decades of custom. New townships cannot manufacture this.
Ethnic balance that widens the market
Close to even Chinese and Malay. A concept serving both has an unusually large base here.
Who actually walks past your door
Estimated share of retail spend, by ethnicity and customer type. Read the last row before you commit.
| Segment | Share | Per visit | When | Concepts that win them |
|---|---|---|---|---|
| Chinese Malaysian working households | 40–45% | RM12–35 | Daily, morning and evening | Hawker food, kopitiam, gold, pharmacy, hardware |
| Malay working households | 33–38% | RM10–30 | Daily; strong in Ramadan | Halal food, mini-mart, pharmacy, phone shops |
| Indian Malaysian households | 12–15% | RM12–35 | Evenings and weekends | Mamak, clinics, gold, provision |
| Students from UTM and nearby colleges | 8–12% | RM10–25 | Term-time | Cheap eats, printing, barber, phone repair |
| Migrant workers | 6–10% | RM8–20 | Evenings and Sunday | Remittance, phone top-up, cheap food, groceries |
| Premium or Singaporean trade | <3% | — | Effectively absent | Premium concepts do not clear here at any rent. |
Ethnic composition
2022 citizen electoral roll for the P.161 Pulai federal constituency, which contains this precinct. The roll counts registered voters only — it excludes non-citizens (migrant workers, Singaporeans, expatriates) and everyone under 18. Source: ElectionData.MY.
A near-even seat: 45.9% Malay and Bumiputera to 40.3% Chinese, with 12.2% Indian. That balance is why the Skudai and Pulai strips sustain a hawker economy and a halal one side by side, and why single-community positioning leaves a large share of the market on the table. TUTA’s own street mix is close to the seat average, which is exactly why a hawker economy and a halal one trade side by side here.
Catchment and market depth
Scale indicators for this precinct.
Rent and price schedule
Market bands, September 2026. Corner, frontage and existing tenancy change everything.
| Level & position | Monthly rent | Best suited to |
|---|---|---|
| Ground floor | RM2,500–6,300 | Anchor F&B, retail, clinic, salon |
| 1st floor | RM1,000–2,000 | Studio, tuition, spa, private dining |
| 2nd floor | RM700–1,500 | Back office, storage, co-working |
| Whole block | RM4,000–8,000 | Multi-floor F&B, medical, corporate |
| Asset | Asking range | Gross yield |
|---|---|---|
| Shophouse, intermediate | RM650k–1.3M | 4.5–5.5% |
| Shophouse, corner | RM1.4M–1.75M | 4.5–5.5% |
| Reference: 51 recorded transactions at a median of RM1,120,000 and RM741 per sq ft (June 2024 – May 2025). Source: brickz.my, from JPPH transaction data. | ||
What is missing — the opportunity list
Compiled from listings, directories and on-the-ground survey. Absence of evidence is not proof of absence — verify before you commit.
The honest assessment
Every agent will tell you the first column. Read the second one twice.
- Second-highest turnover in Johor Bahru. Fifty-one recorded transactions. Deep, liquid market.
- Genuine seven-day daily footfall. Volume trade, not occasion trade.
- Healthy yield at 4.5–5.5%. Low entry price with reliable demand.
- The widest ethnic base in western JB. Close to an even Chinese and Malay split.
- Low ticket caps your commission. A RM1.12 million median. Three deals here equal one in Sutera Utama.
- Ageing stock and dated fit-outs. TUTA was built out decades ago. Budget for higher renovation and confirm three-phase power.
- Price-sensitive customer. Average spend RM10–35 a head. Premium concepts fail here regardless of rent.
- Parking is congested. High footfall on an old street grid. Saturday is the binding constraint.
- No cross-border or premium layer. Single-segment mass market. No second customer if local spending softens.
How it compares with the other JB strips
Ground-floor asking rents from live portal listings, September 2026.
| Strip | GF rent / month | Who shops there | Parking | Pick it if |
|---|---|---|---|---|
| Mount Austin | RM3,800–9,500 | Dense local Chinese Malaysian; highest weekday volume in JB | Congested | Your model needs volume seven days a week and you can live without parking. |
| Bukit Indah | RM2,500–4,200 | AEON-anchored footfall plus Singaporean day-trippers | Adequate | You want an Eco Botanic customer at roughly half the rent. |
| Eco Botanic | RM6,000–15,000 | Singaporean weekenders, EduCity students, expat families | Free, ample | You want high basket size and can survive a soft Monday–Thursday. |
| Taman Molek | RM4,500–15,000 | Affluent Chinese Malaysian, expat and Singaporean | Tight | You are an evening or bar operator with an existing following. |
| Sutera Utama | RM3,500–25,000 | Affluent Skudai households; the state’s highest median price | Adequate | You sell premium and need a catchment that pays for it. |
| Johor Jaya | RM2,200–4,500 | 66,000 residents; the most balanced ethnic mix in JB | Adequate | You want the healthiest yield and the deepest deal flow. |
| City Centre / IIBD | RM5,000–13,000 | Singaporean walk-in via CIQ; RTS terminus January 2027 | Paid / limited | You want walk-in cross-border traffic and will pay for the story. |
Ground-floor asking rents from live portal listings, September 2026. Expect 5–15% negotiation room on any of them. We will tell you honestly when another strip is the better commercial decision for your concept.
Buying, not renting? Same area, the residential side — NAPIC registered transactions, median price, median PSF and the 12-month move: Taman Ungku Tun Aminah landed data → · condos · industrial
What it actually costs to open here
Rent is the number everyone quotes. It is rarely the number that kills the deal — the fit-out is.
| Item | Amount (RM) | Basis |
|---|---|---|
| Fit-out — full F&B with kitchen | 231,000 – 539,000 | RM150–350 psf on 1,540 sq ft. Kitchen exhaust, grease trap and M&E are what push it up. |
| Fit-out — basic retail (indicative) | 150,000 – 280,000 | Mid-range commercial guidance; no retail-specific Malaysian benchmark is published. |
| Deposits — 2 months + 1 advance + ½ utility | 15,400 | The Malaysian “2 + 1 + ½” convention, payable before you touch the unit. |
| Stamp duty on the tenancy | 211 (1 yr) / 633 (3 yr) | RM1 per RM250 of annual rent for ≤1 year; RM3 for 1–3 years. The RM2,400 exemption was abolished in January 2025. |
| Legal fee — tenancy agreement | 1,320 | Solicitors Remuneration Order 2023, Second Schedule: for a tenancy at RM10,000/month or less, 30% of one month rent (min RM500). Above RM10,000/month the rate steps down to 15–25%. A lease (term over three years, common on commercial units) is charged separately and higher — 60% of one month rent up to RM10,000, then 30–50%. |
| Agent commission | 0 | 1.25 months rent, paid by the landlord by convention. A tenant paying this is being overcharged. |
| TNB three-phase connection + deposit | 4,300 – 6,900 | RM1,700 connection plus RM2,600–5,200 deposit at 10–20 kW. Deposit earns 2.5% p.a. and is refundable. |
| Licences — premise + signboard, first year | Budget 700 – 1,200 | Premise licence fees are set by your own council (MBJB / MBIP / MBPG / MPKu) by business type and floor area — confirm with them. Signboard licence RM200–400. This line is a planning allowance, not a quoted fee. |
| Sdn Bhd incorporation | 1,000 | SSM fee. A foreigner cannot register a sole proprietorship. |
| Realistic total before you sell anything — F&B | 255,400 – 575,400 | Plus opening stock, POS, signage design, insurance and 3 months working capital. |
Cost model, licences, the full FAQ and sources & method are on one page: the Johor Bahru shop lot guide.
Two ways we can help
We hold ready units here that are never listed publicly, and current developer rebate sheets for the new phases.
Tell us the concept. We will send matching units within 24 hours.
Most good ground-floor units in TUTA change hands before they are advertised. Send us your trade, floor area, budget and target opening date, and we will come back with what is actually available — including units where the current tenant is quietly looking to assign.
- Off-market and tenancy-assignment units
- Floor plans, actual outgoings and licensing feasibility
- Foreign-buyer and non-resident tenancy guidance
Or WhatsApp / call +60 10-906 6685 · email
No fee to tenants and buyers. Reply within one working day.
Get the current new-launch rebate sheet for this corridor.
New commercial phases carry incentives that are never published — early-bird discounts, rebates, rent guarantees and fit-out allowances that shift monthly. We will send you the live sheet with the yield maths done.
- Live rebate and package comparison across projects
- Net yield modelling after outgoings and financing
- Foreign purchase threshold and state consent levy notes
Or WhatsApp / call +60 10-906 6685 · see new launches
Includes the RM1M foreign-buyer floor and the 3% state consent levy for Johor commercial property.
Questions people actually ask
Short, direct answers.