SO/ Kuala Lumpur Residences @ Oxley Towers KLCC
Five hundred and ninety freehold residences above the SO/ hotel in Tower 1 — construction finished in August 2025, handovers began in September 2025, and the scheme was 58% sold as at 15 September 2025.
⚡ Typical reply within 15 minutes, 9am–10pm MYT · No obligation
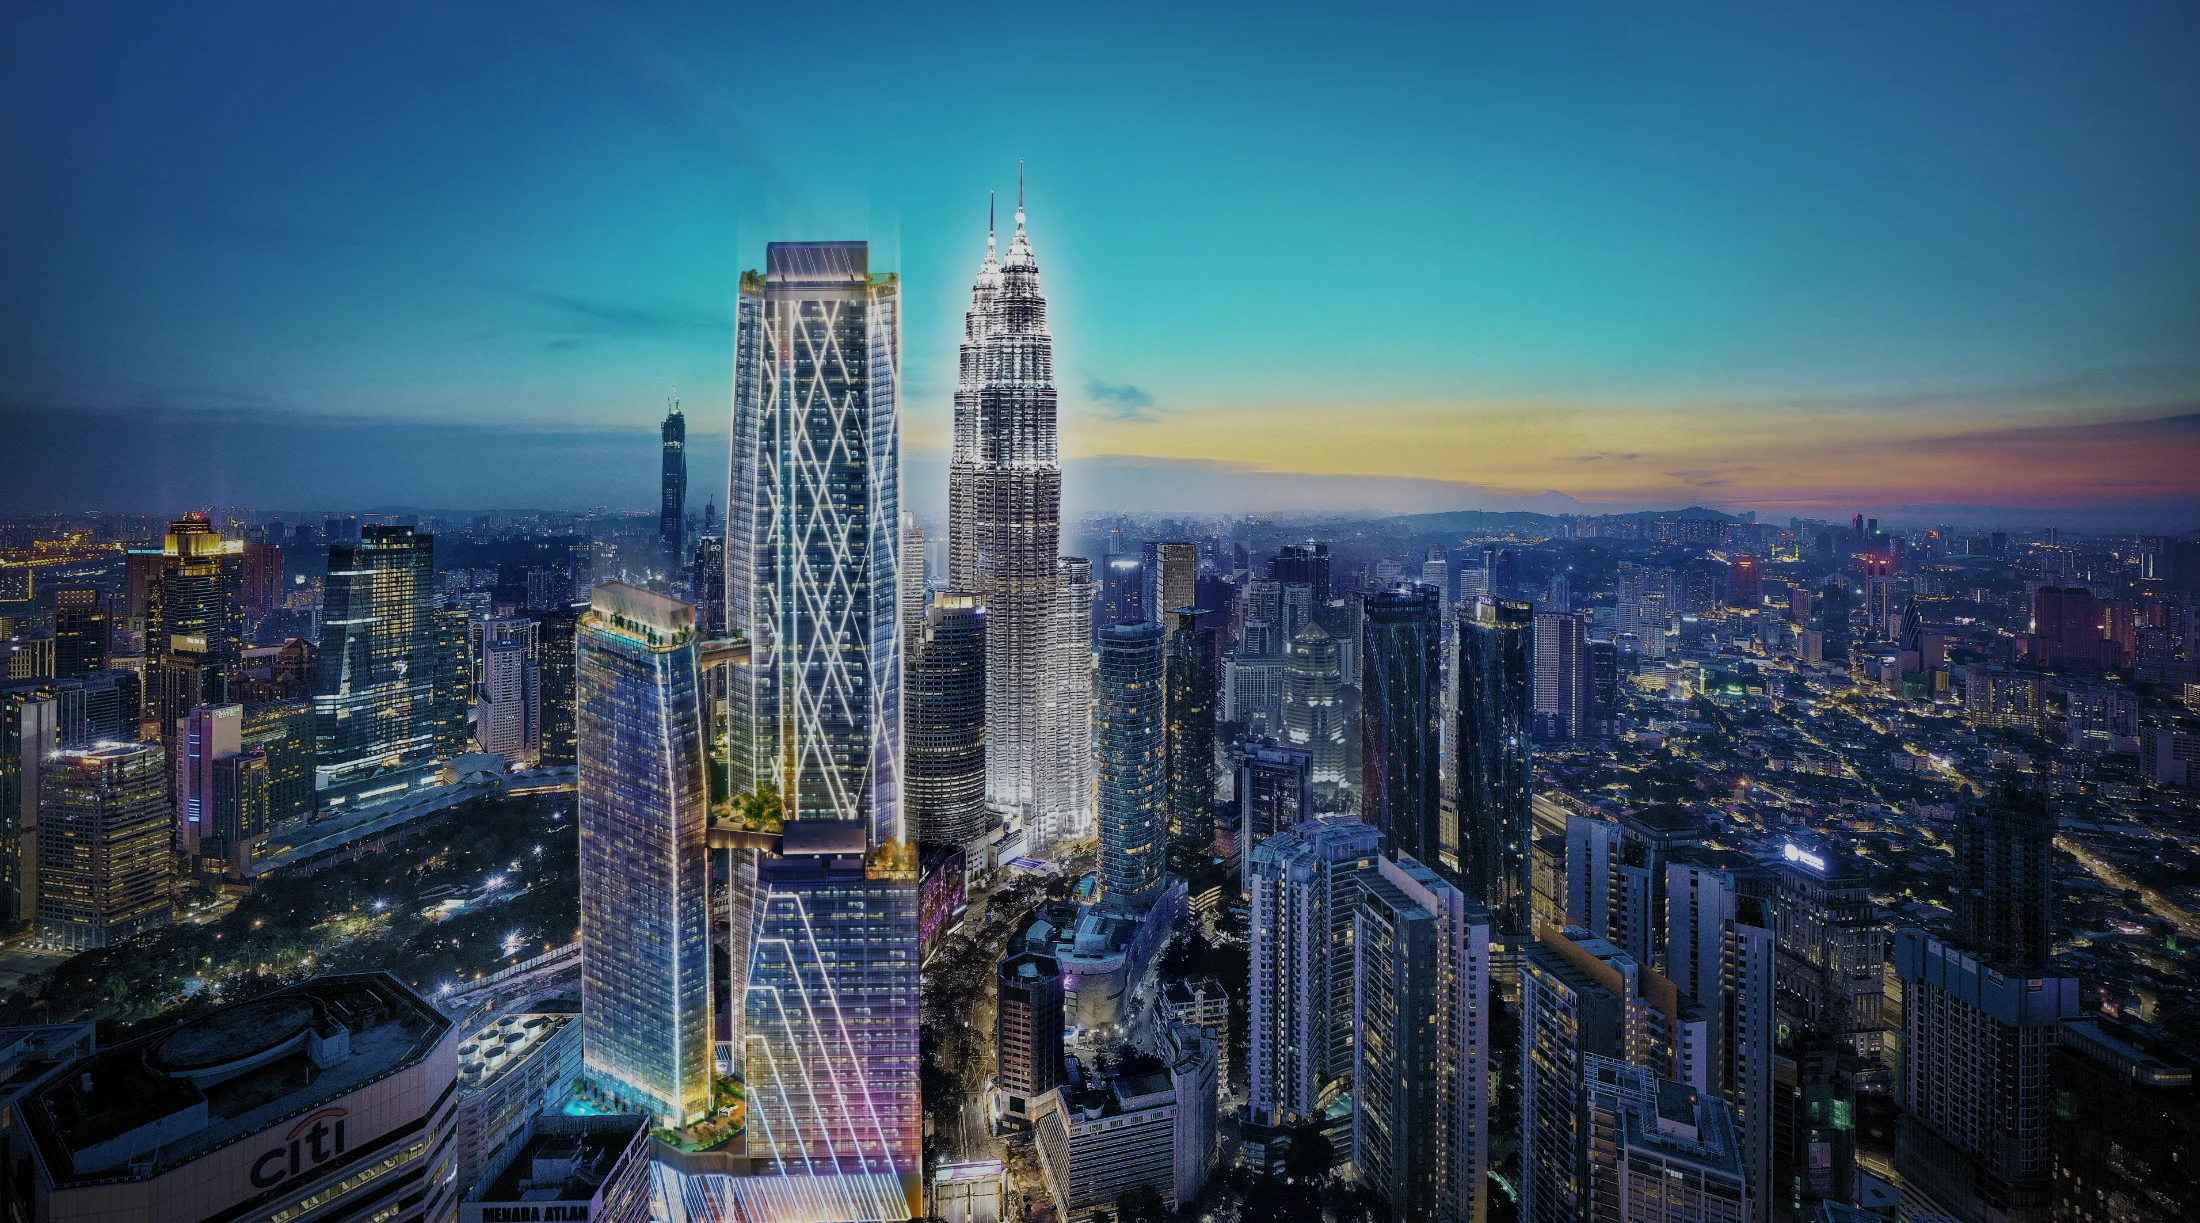
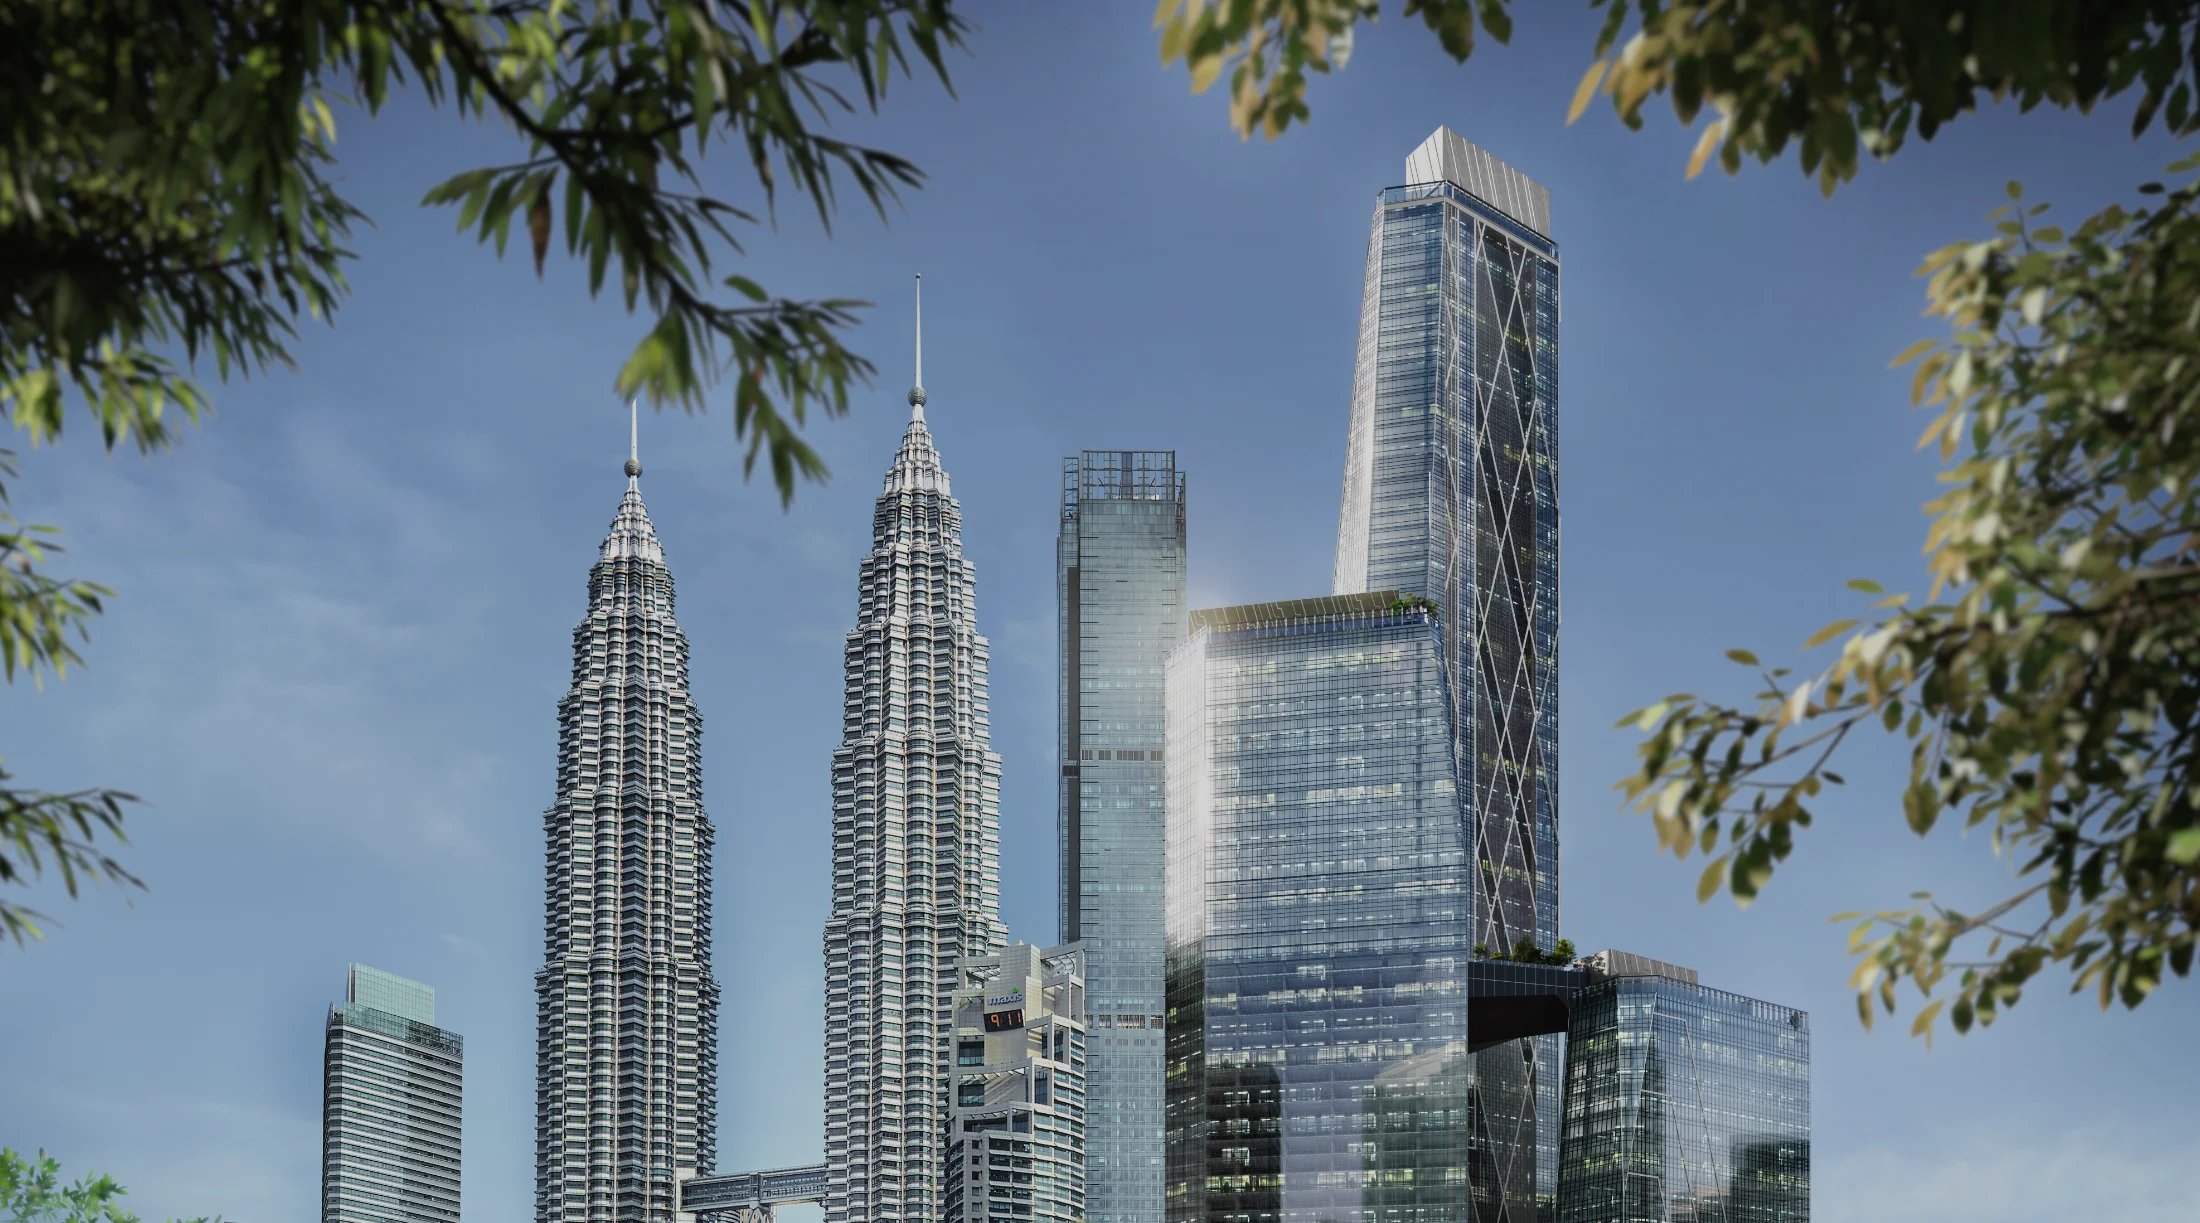
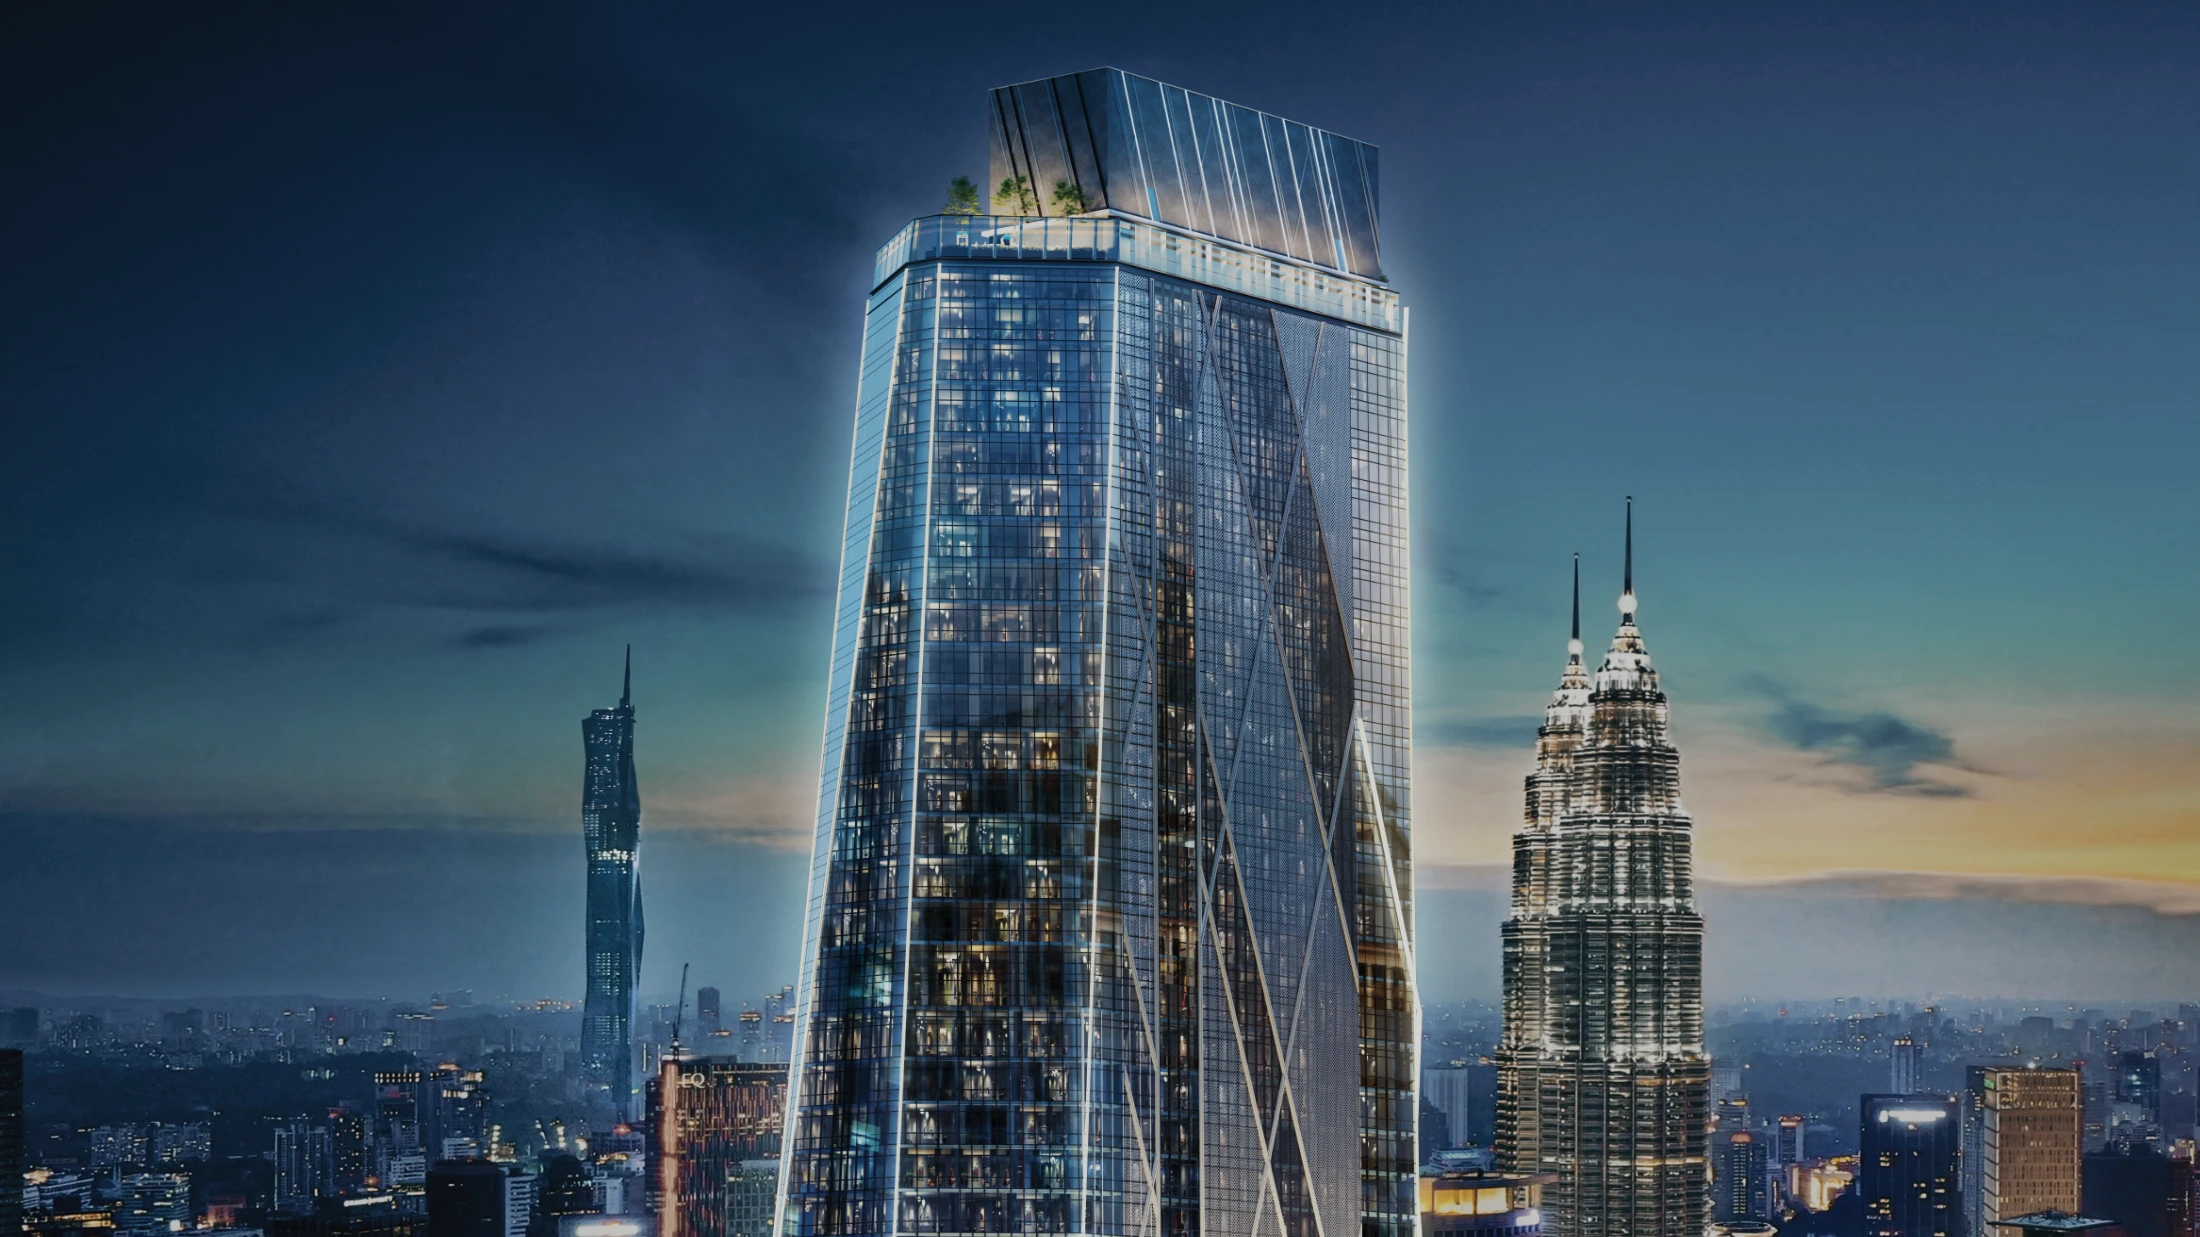
SO/ Kuala Lumpur Residences @ Oxley Towers KLCC at a glance
Everything below comes from a source that belongs to Oxley: the FY2025 annual report of the listed parent, its corporate announcements, and the project website at oxleytowers.com.my. Where those three disagree — and on this project they disagree more than once — both figures are printed rather than the flattering one. Where nothing has been published, the row says so instead of guessing.
- Development
- SO/ Kuala Lumpur Residences, Tower 1, Oxley Towers KLCCOxley Rising Sdn Bhd (1053340-P); parent Oxley Holdings Limited (201005612G), SGX Main Board
- Tenure
- FreeholdThe FY2025 annual report classifies the whole scheme as Residential, Retail, Hotel and Office; no separate title category is published for the residences
- Tower and storeys
- Tower 1 — 78 storeysOfficially described as “SO/ Kuala Lumpur Hotel and Residences”
- Units
- 590 residences above a 226-room hotel857 residential units across the scheme, counting the 267 Jewel Residences in Tower 2
- Published layouts
- Nine · 566 – 995 sq ft53–92 sqm, all on the typical floor layout for levels 34–43 and 47–51
- Construction
- Completed August 2025Announced 29 August 2025; the annual report states construction was completed in August 2025
- Handover
- First units handed to buyers September 2025Vacant possession of both towers was under way as at 29 August 2025
- Sales status
- 58% sold as at 15 September 2025Annual report figure. About RM550 million of premium inventory was retained as at August 2025
- Site and GFA
- About 12,554 sqm (about 3.10 acres) · GFA 175,979 sqmWhole three-tower scheme, not the residential component alone
- The SO/ hotel
- Not openBoth hotels were in final fit-out; the first is targeted to begin operations by Q4 2026
- Foreign buyer price floor
- RM1,000,000 in Kuala Lumpur“Foreign interest” includes Malaysian permanent residents; state consent needed under section 433B
- Not published
- GDV, maintenance charge, sinking fund rate, CCC or OC dateAlso unpublished: the exact level split between hotel, residences and office, and any coordinate for the building
Explore related topics
Curated hubs, each with its own guide — not auto-generated tag archives.
Six things to work out before you buy at SO/ Kuala Lumpur Residences
This is a finished freehold tower in KLCC that you can walk into and inspect, which is rarer than it sounds. It is also a building where roughly 42% of the scheme was still unsold a year ago, where the branded hotel underneath has not opened, and where a non-citizen pays 8% stamp duty going in and 30% on the gain coming out within five years. All of that is true at the same time, and all of it is arithmetic you can do before you commit.
The 8% stamp duty on a RM2.22 million unit is RM177,600
From 1 January 2026 a non-citizen buying residential property in Malaysia pays a flat 8% stamp duty on the transfer instrument. No tiering, no first-home relief, and the Finance Act 2025 expressly lists service apartments and SOHOs as residential — so do not assume a serviced-residence label puts you outside it. The only price point on this project I can defend is the developer’s own bulk deal: 100 units for about S$67 million, roughly RM222 million, which works out at about RM2.22 million per unit. Eight per cent of that is RM177,600, payable at transfer, in cash, on top of legal fees, consent costs and valuation. That single line is larger than the total transaction cost most buyers budget for. Run it against your actual negotiated price before you decide anything.
RPGT is 30% for five years, then 10% forever — there is no zero band
A non-citizen or a foreign company disposing of Malaysian property pays Real Property Gains Tax at 30% within five years and 10% from the sixth year onward. Malaysian citizens eventually reach a zero rate; you do not. The rate simply steps down to 10% and stays there for as long as you own it. Now combine that with the entry cost. On a RM2.22 million purchase, the RM177,600 stamp duty only comes back to you if the price rises enough that 70% of the gain covers it — that is a gain of about RM253,700, roughly 11.4% on the purchase price, just to break even on one tax while the other tax is taking its cut. Hold past five years and the arithmetic softens: you then need about RM197,300 of gain. That is why a short hold here is punishing, and it is why I would not buy this as a two-year trade.
On a completed unit, the balance is due now — not progressively
Foreign buyers in Malaysia are typically offered a loan margin of 60% to 70%. On a RM2.22 million unit that means a loan of RM1.33 million to RM1.55 million, and a cash gap of RM666,000 at 70% or RM888,000 at 60%. Add the RM177,600 stamp duty and you are looking at roughly RM843,600 to RM1,065,600 of cash before legal fees, consent application costs, valuation and any furnishing. The part buyers miss is the timing. On an off-plan purchase the balance is drawn down in stages over three or four years while the building goes up. This building is finished, so completion happens on the ordinary conveyancing timetable and the whole balance falls due at once. Get your loan approval in principle in writing before you sign, not after.
Your main competitor is the developer, and it can discount
The FY2025 annual report puts the scheme at 58% sold as at 15 September 2025 — so roughly 42% was still unsold, and about RM550 million of premium inventory was being retained as at August 2025, which the group said it aimed to sell within the next 6 to 12 months. That is not a footnote; it is the shape of your resale market. A private owner reselling a unit competes with a developer that can rebate, absorb legal fees, throw in furnishing, bundle a car park, or simply cut the price on a whole block of stock in one decision. You cannot do any of that. Until that retained inventory clears, the developer sets the ceiling on what your unit can fetch. Before you buy, ask what the developer is currently offering on unsold stock in the same stack — that number, not the listing portal, is your real comparable.
The branded-living promise has not started yet
Accor renamed the brand from SO Sofitel to SO/, and the residences are officially positioned, in the chief executive’s own words on 2 June 2025, “above the iconic SO/ Kuala Lumpur Hotel”. That hotel is not open. Both hotels on the site were still in fit-out, and the first is targeted to begin operations by Q4 2026 — a target, not a commitment. The group has also said it intends to divest the hotel business when the opportunity arises. And read what the developer itself publishes under the Accor branding: “SO/ Kuala Lumpur Residences is not owned, developed or sold by Accor or its affiliates. Oxley Rising Sdn. Bhd., a company organised under the laws of Malaysia, is independently owned and operated and is solely responsible for the ownership, development, and operation of this Project herein.” That is a brand-licence carve-out. It puts operation of the residences squarely on the developer. Buy the flat and the location; do not pay a premium for a hotel service that has not opened and an operator that may change hands.
What is genuinely solid here: it is finished, and you can inspect it
Set the accounting noise aside for a moment. Construction completion was announced on 29 August 2025, the annual report confirms the works were completed in August 2025, and the first residential units were handed over to buyers in September 2025. The office tower was finished in early 2025 and handed to Alliance Bank as its new owner; the retail element is fully sold and is to be managed by Pavilion Group. Those are third parties who took delivery, which is a harder test than a rendering. For you it means you are not buying a promise: you can walk the corridors, see the actual finishes, check the lift waiting times, meet the management office, and measure your own unit against the strata plan. On a freehold KLCC address that is a materially better position than buying off plan, and it is the single strongest reason to look at this project rather than a launch.
The whole development, decoded
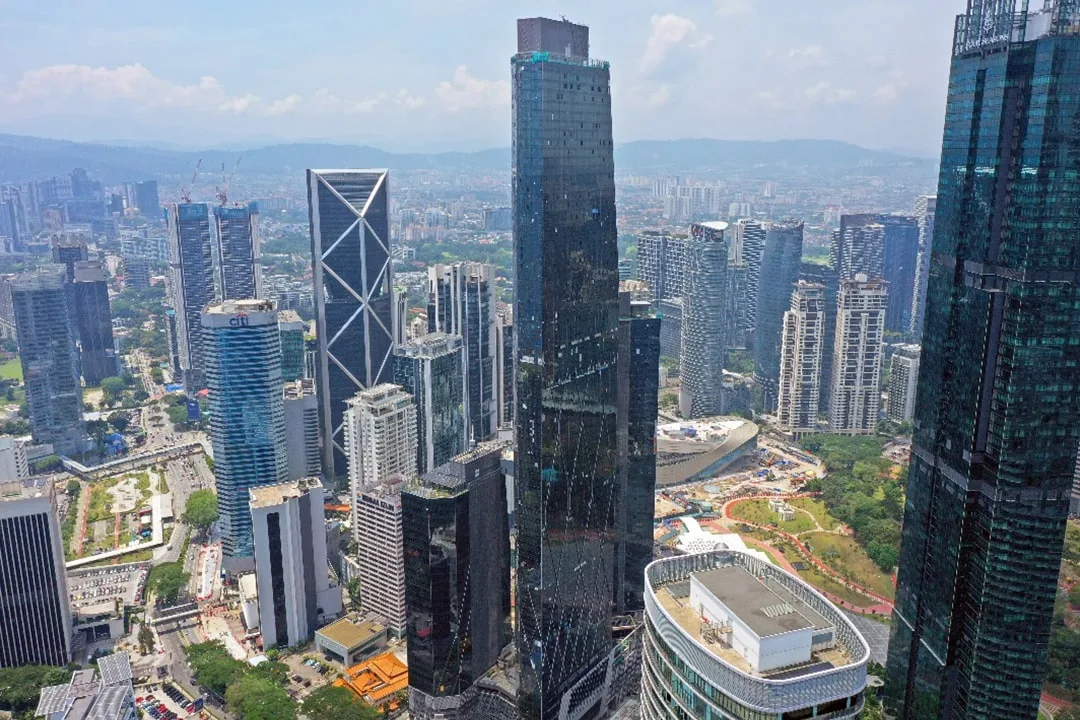
Three towers on about 3.10 acres, sharing a retail podium. One of them — Tower 1 — is the subject of this page: a 78-storey tower with a 226-room hotel at the bottom and 590 residences above it. The other two are worth understanding because they are your neighbours, your lift traffic and, in the case of Tower 2, the asset that carries the impairment now hanging over the parent’s accounts.
Three towers, one site — and only one of them is this page
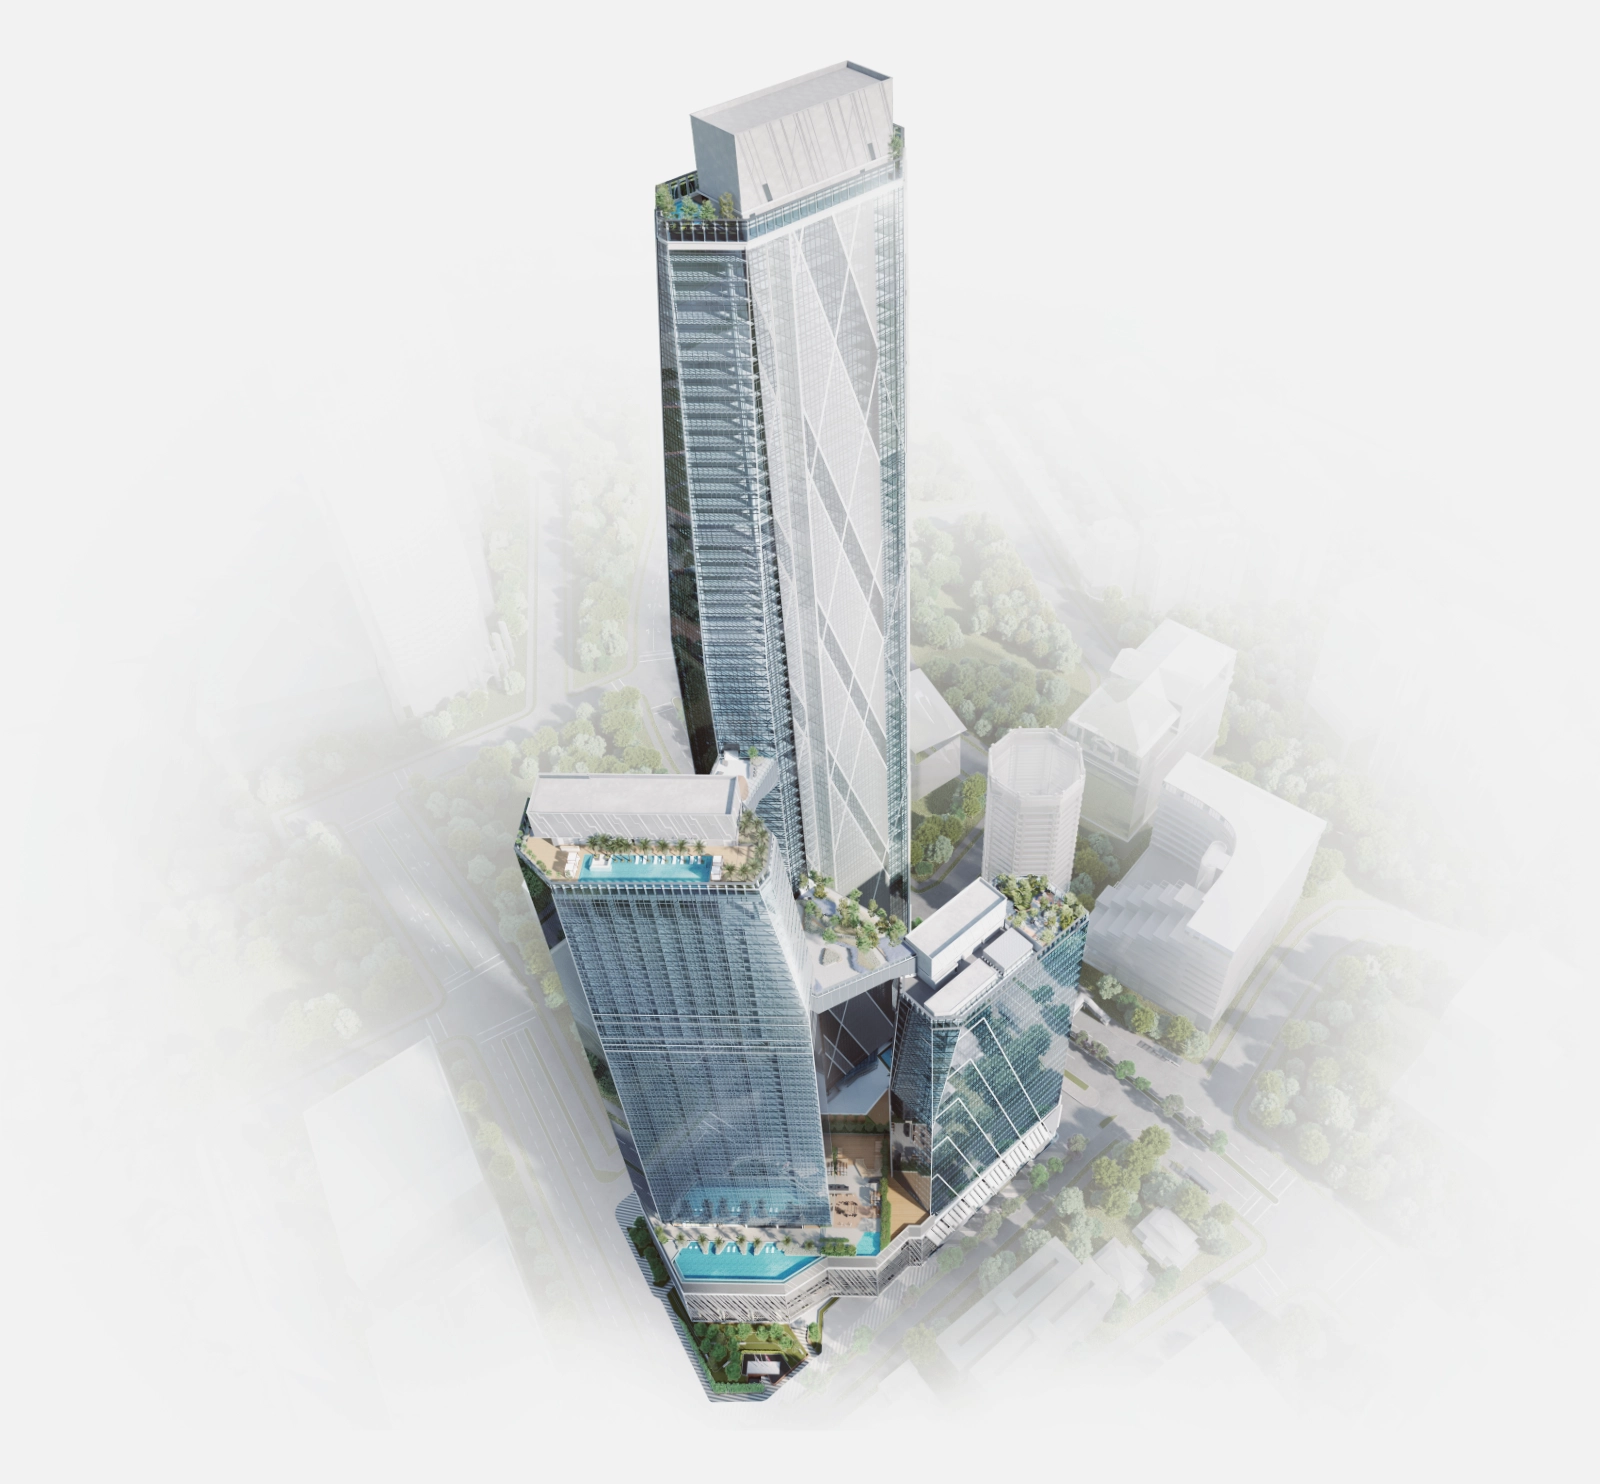
SO/ Kuala Lumpur Hotel and Residences
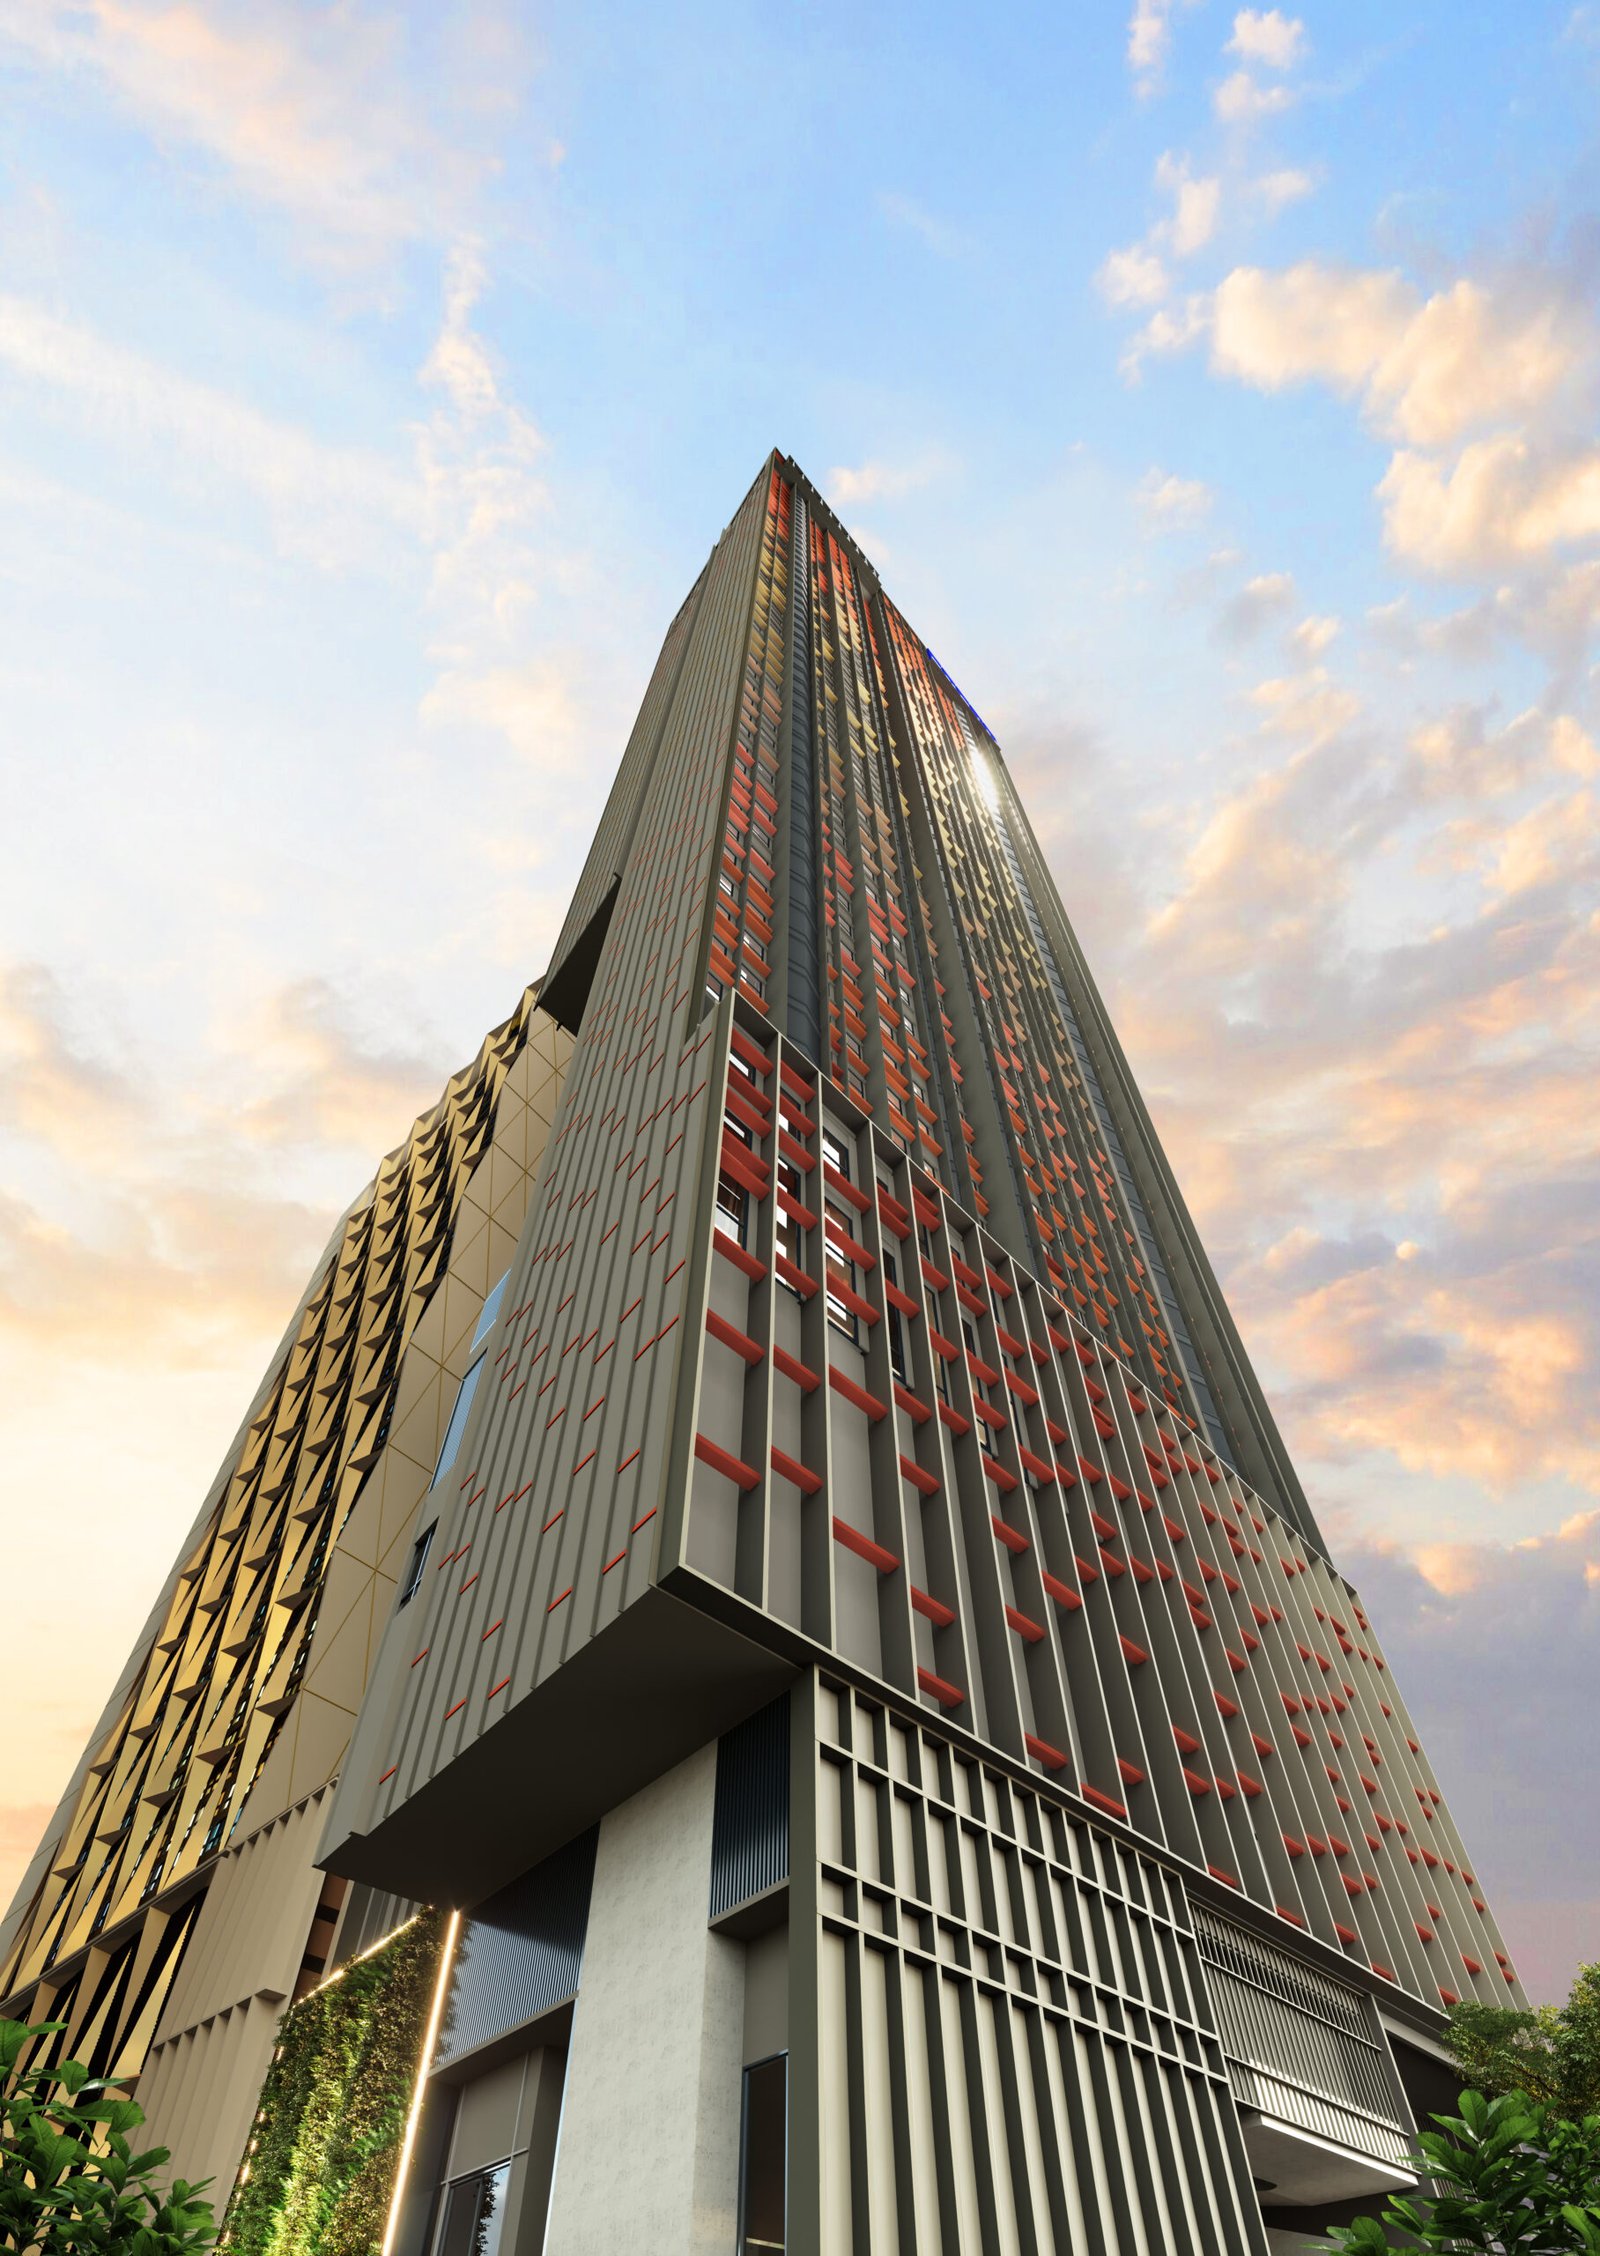
This is the tower this page is about. Officially described as “SO/ Kuala Lumpur Hotel and Residences”, it is a 78-storey tower carrying the 226-room SO/ Kuala Lumpur Hotel with 590 residences above it — the chief executive’s own phrasing on 2 June 2025 was “Positioned above the iconic SO/ Kuala Lumpur Hotel”. Construction completed in August 2025 and the first units were handed to buyers in September 2025. The hotel itself is not open; it was in final fit-out and the first hotel on the site is targeted to begin operations by Q4 2026. Oxley does not publish which levels are hotel and which are residences, so if the floor split matters to you — for lift banks, for noise, for your own floor level — ask for it in writing.
The Langham Kuala Lumpur and Jewel Residences
The second tower carries The Langham Kuala Lumpur hotel and the 267-unit Jewel Residences, which is a separate product from the one on this page. Two things about it are worth carrying in your head. First, the key count contradicts itself in Oxley’s own documents: the project website says “THE LANGHAM, KUALA LUMPUR — 198-KEY LUXURY HOTEL”, while the FY2025 annual report says 213-room, twice. The annual report is both more recent and more authoritative. Second, this is the hotel in the RM250 million transaction. On 29 July 2026 Oxley completed the sale of a 30% interest in the luxury hotel, owned by Artisan Hospitality Sdn Bhd — 70% Oxley Rising, 30% Kindway Express Limited — which “will be managed under the Langham brand”. That deal is Tower 2, not the SO/ hotel, and it is routinely misreported as though it were.
Office tower and retail podium
The third tower is an office building, and the retail podium at the base links all three towers together. Both have already changed hands, which is useful information about the scheme as a whole. The office tower completed in early 2025 and was handed over to Alliance Bank, its new owner. The retail element is fully sold and is to be managed by Pavilion Group. As with almost everything structural on this project, the storey count is contradicted inside Oxley’s own publications: the FY2025 annual report calls it “a 26-level office tower”, while the project website calls it a “30-STOREY CORPORATE TOWER” in one place and describes “these 24-floor A-Grade office suites” in another. Three official numbers for one building. I have not found a document that reconciles them, so all three are printed here.
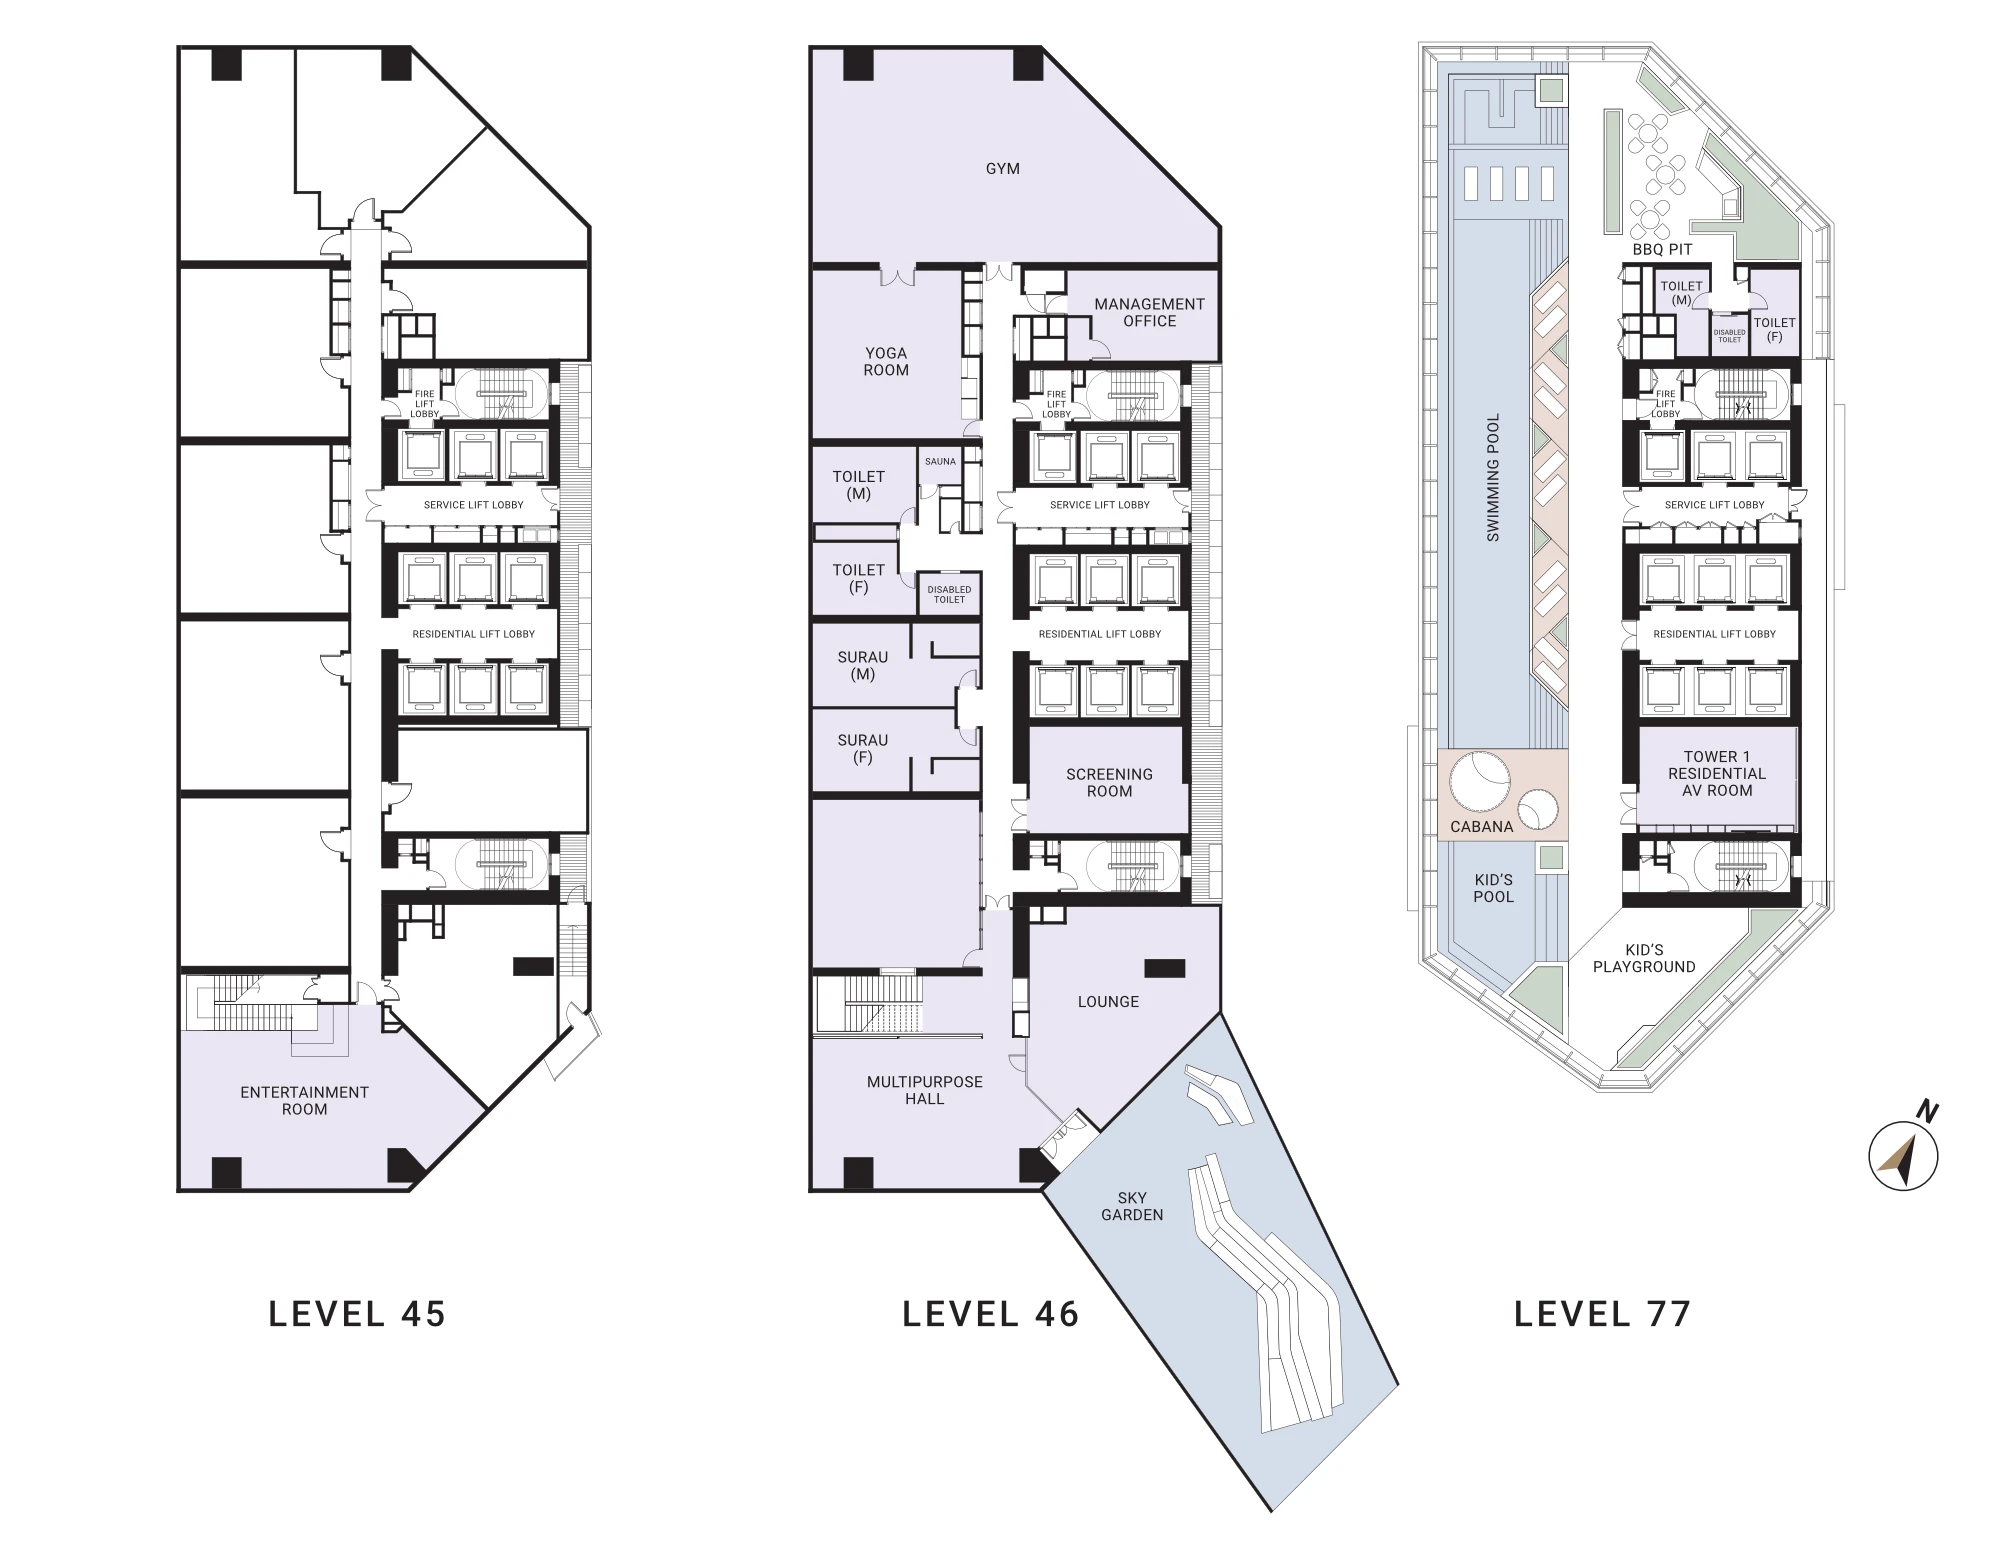
Three storeys of facilities, two of them named by level
The developer publishes “three storeys of facilities” but never publishes a complete level-by-level schedule. Two levels are named in its own marketing — Level 46 for the Sky Garden and Level 77 for what it calls first-class facilities — and a short list of rooms is named with no level attached at all. So the grouping below is honest rather than tidy: where Oxley gives a level, it is shown; where it does not, the item sits in an unallocated group. If a facility matters to you, ask which floor it is actually on and ask whether it is shared with the hotel, because a 78-storey tower with a hotel in the base has two populations using it.
Sky Garden
- Sky Garden — the one facility level Oxley names by floor besides Level 77
- No item-by-item schedule is published for this level
First-class facilities
- Described by the developer as first-class facilities
- Swimming pool — marketed by the developer as Malaysia’s highest residential swimming pool; this is the developer’s claim and I have not seen it independently verified
- No item-by-item schedule is published for this level either
Named facilities with no published level
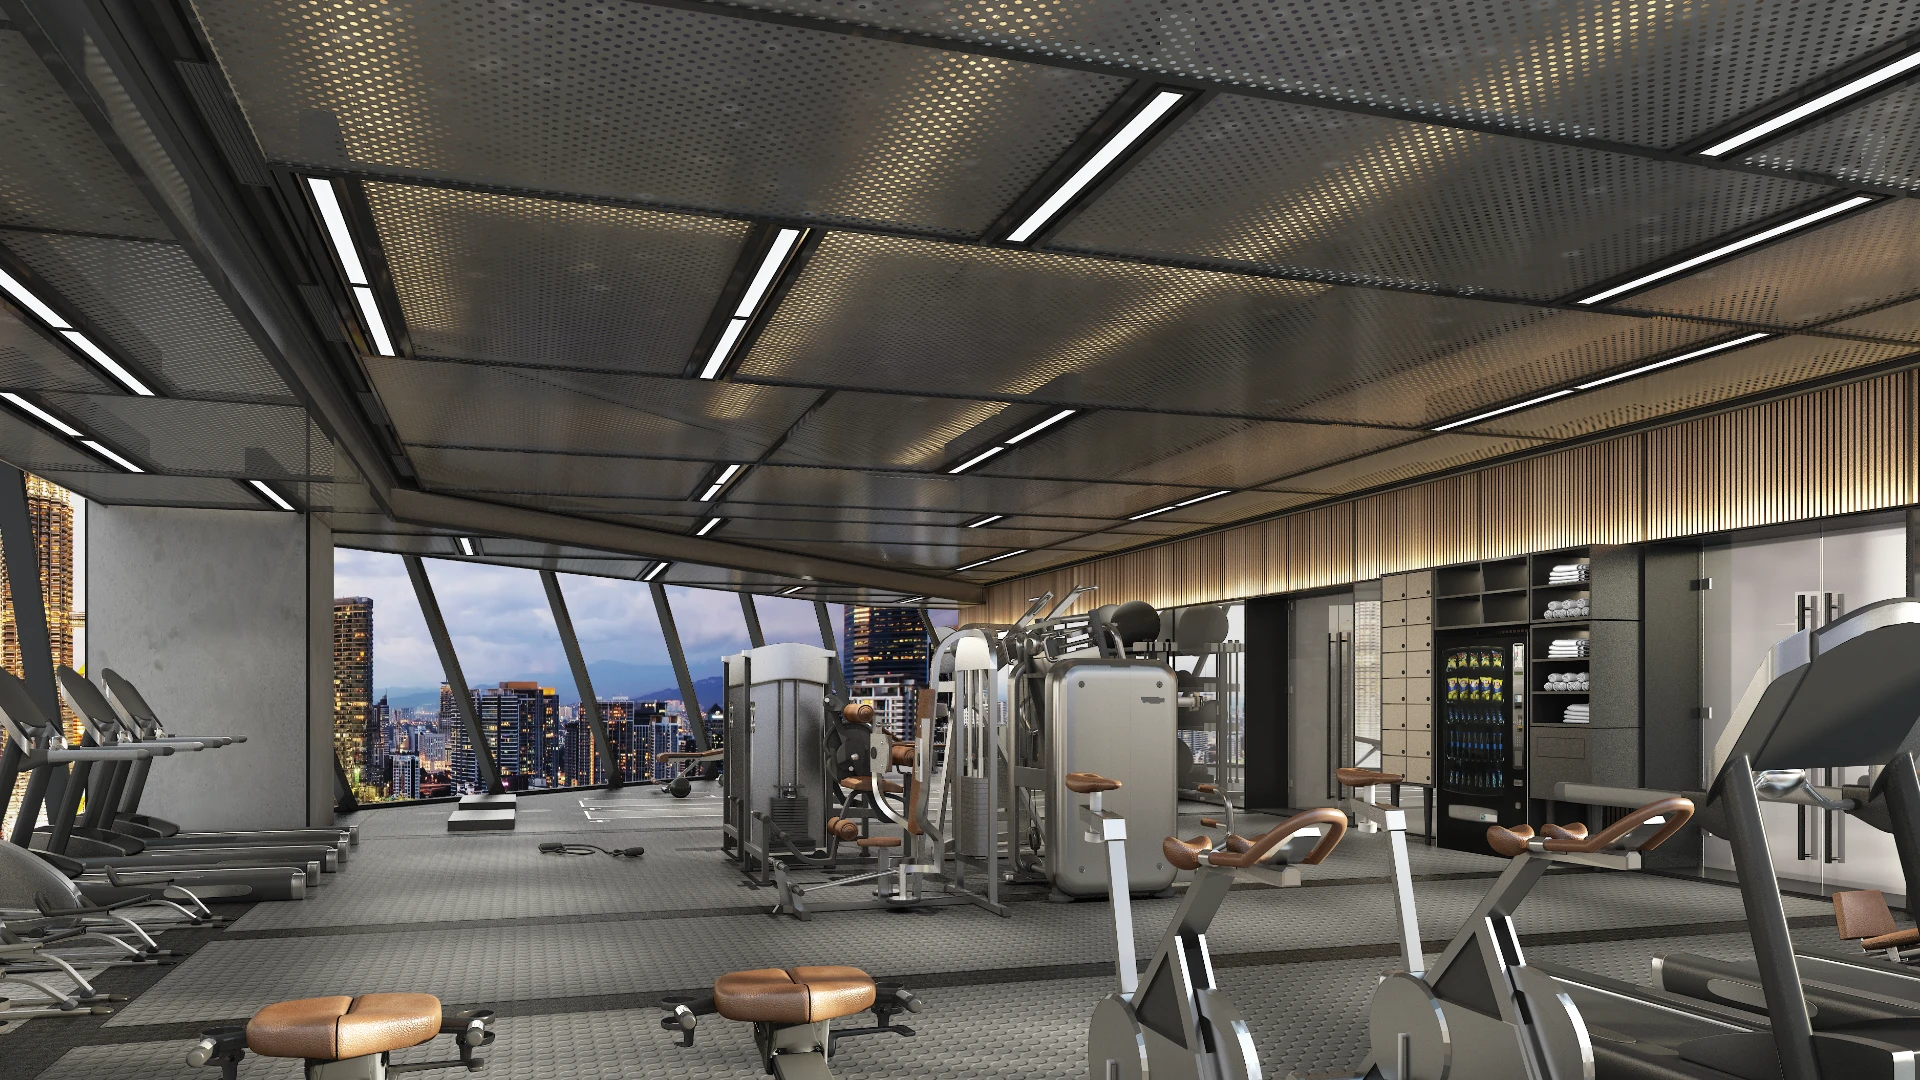
- Gym
- Multipurpose Hall
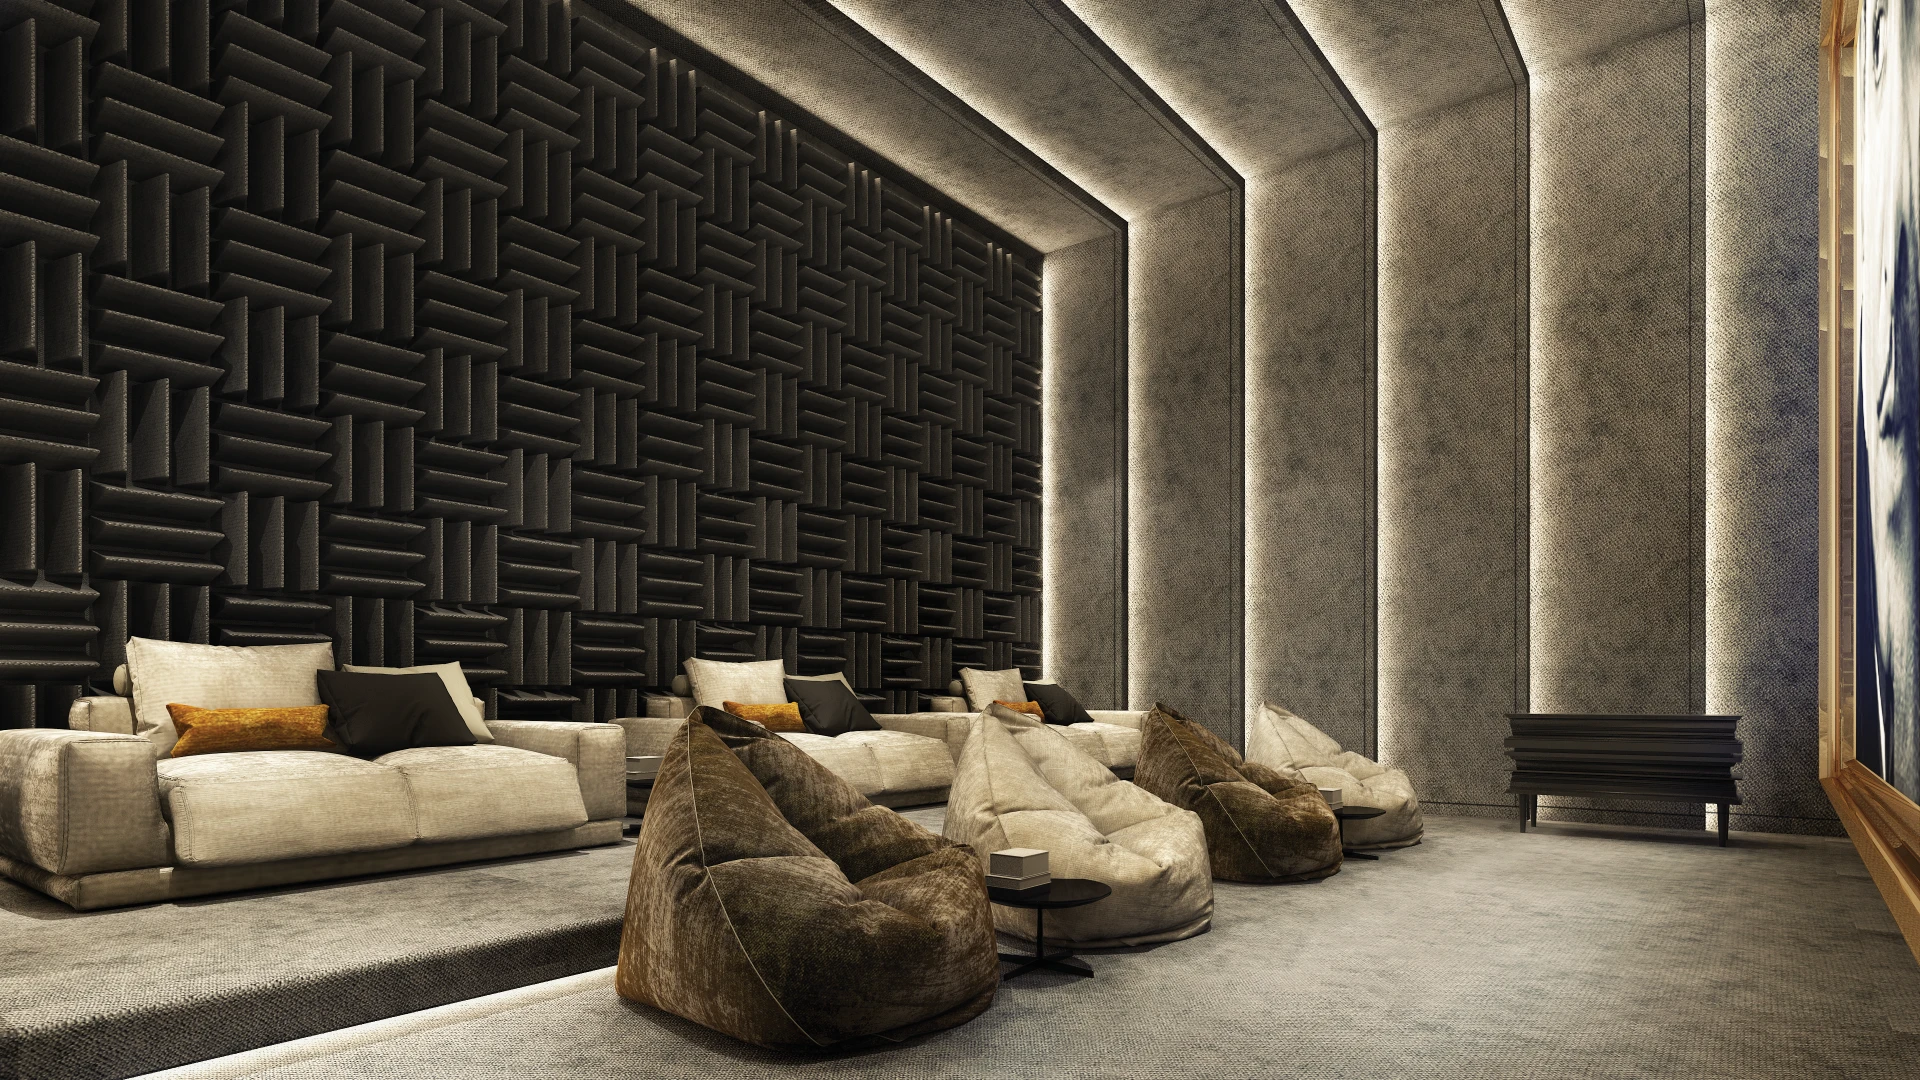
- Screening Room
- Entertainment Room
- 24-hour access to concierge and premium brands — the developer’s marketing wording, with no service scope published
Where the project is now
All 9 SO/ Kuala Lumpur Residences @ Oxley Towers KLCC floor plans
Nine layouts are published, and all nine sit on one drawing headed TYPICAL FLOOR LAYOUT LEVEL 34-43 / 47-51. They run from 566 to 995 sq ft — that is the entire published range, and if you have seen a wider one quoted elsewhere, read the FAQ below before you act on it. Bathroom counts are not printed on any of the nine, so this page does not print them either.
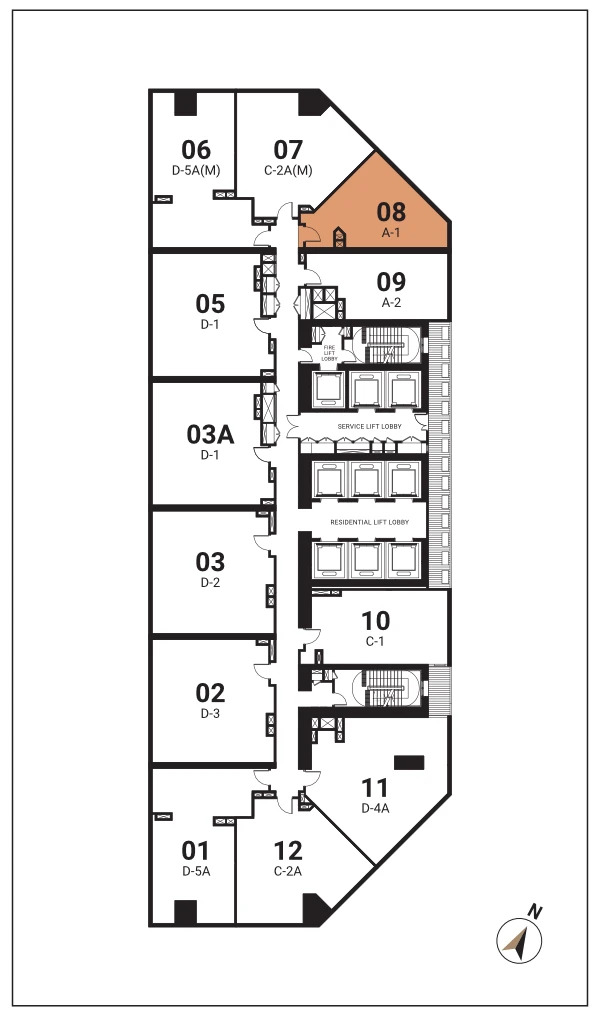
Type A-1 — 578 sq ft
Get this floor plan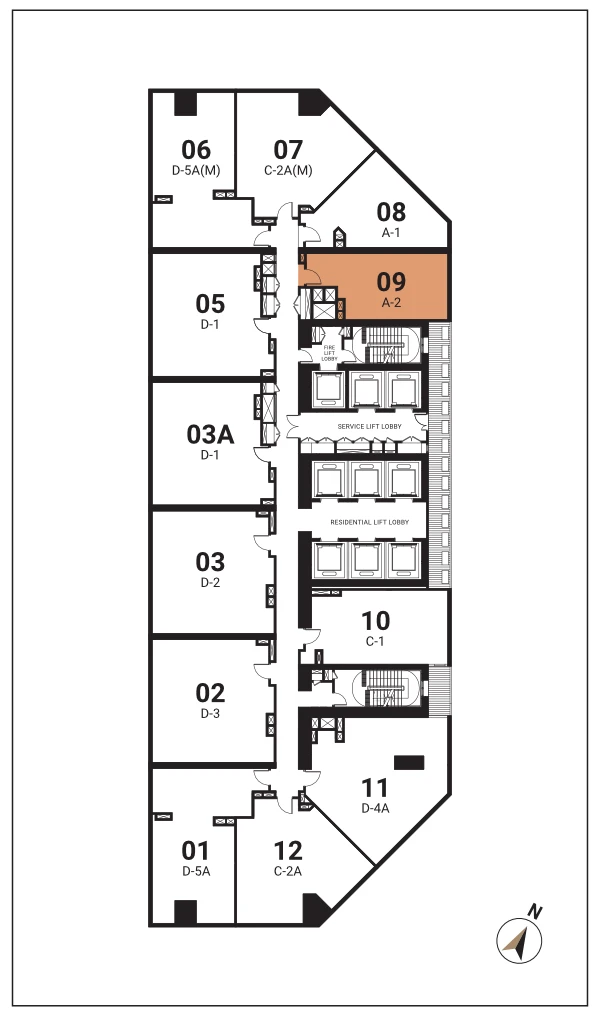
Type A-2 — 566 sq ft
Get this floor plan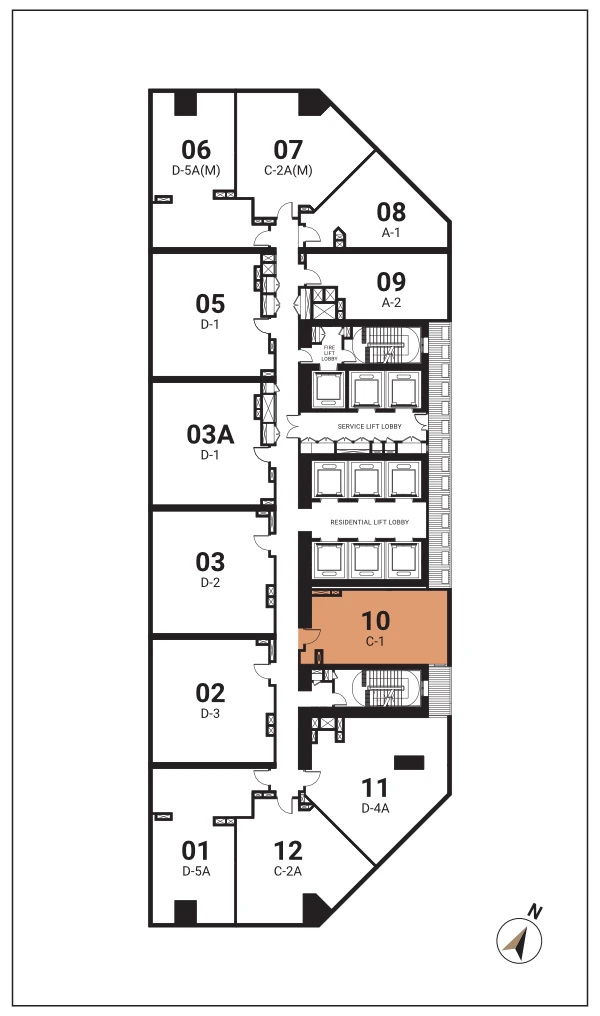
Type C-1 — 711 sq ft
Get this floor plan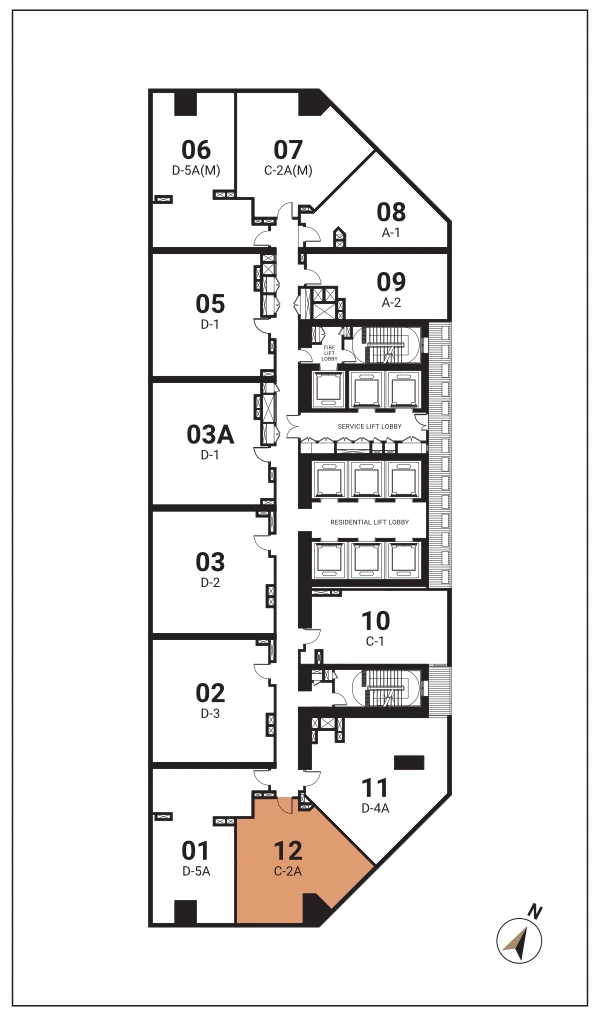
Type C-2A — 815 sq ft
Get this floor plan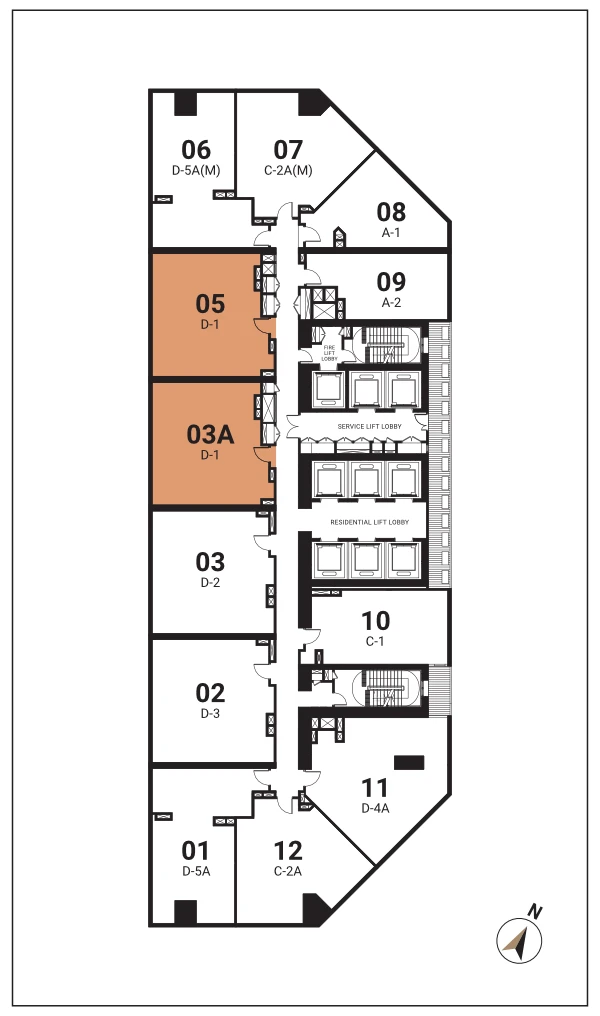
Type D-1 — 903 sq ft
Get this floor plan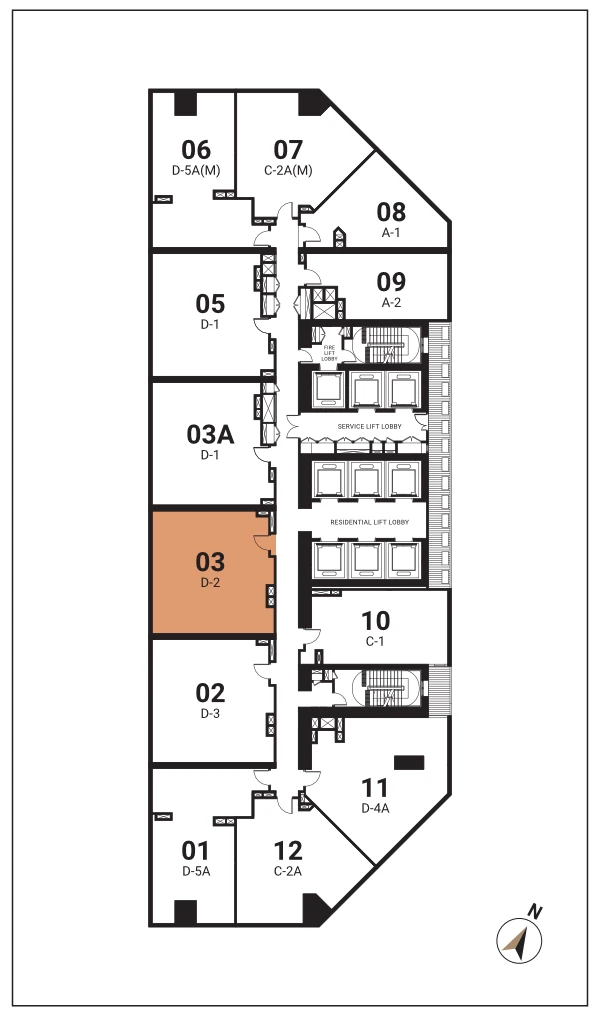
Type D-2 — 956 sq ft
Get this floor plan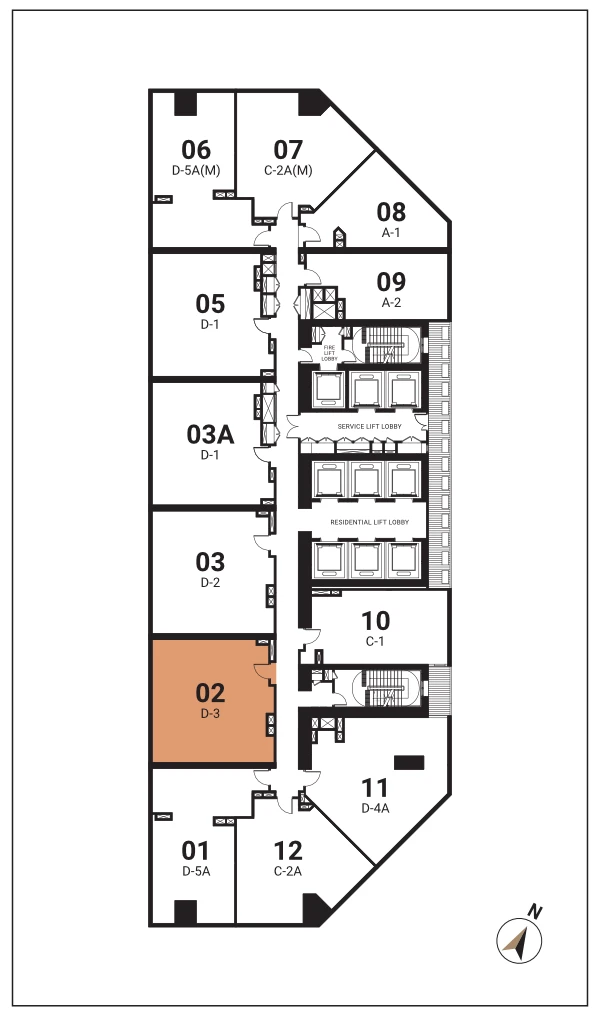
Type D-3 — 956 sq ft
Get this floor plan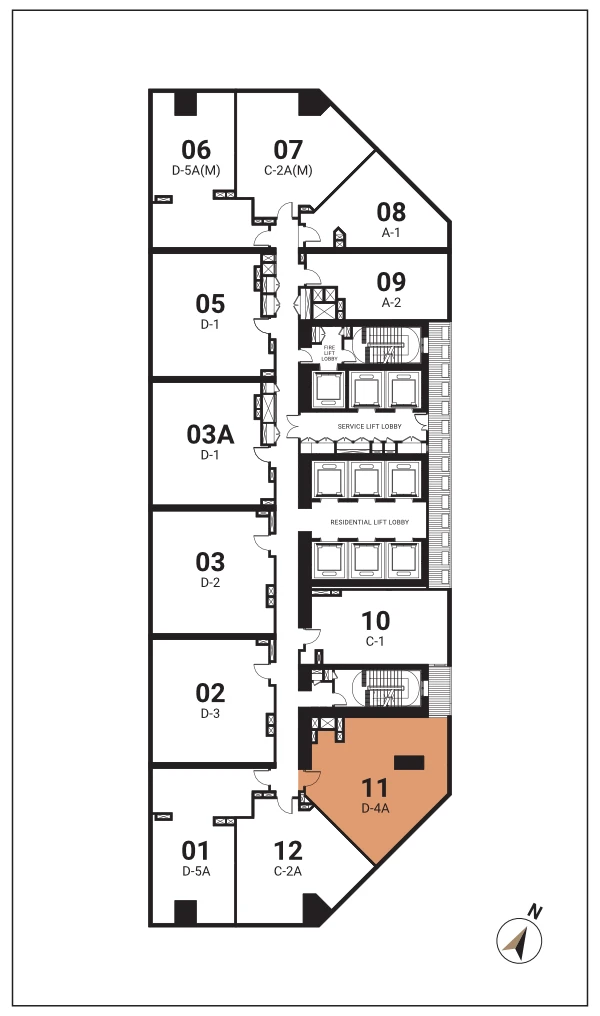
Type D-4A — 995 sq ft
Get this floor plan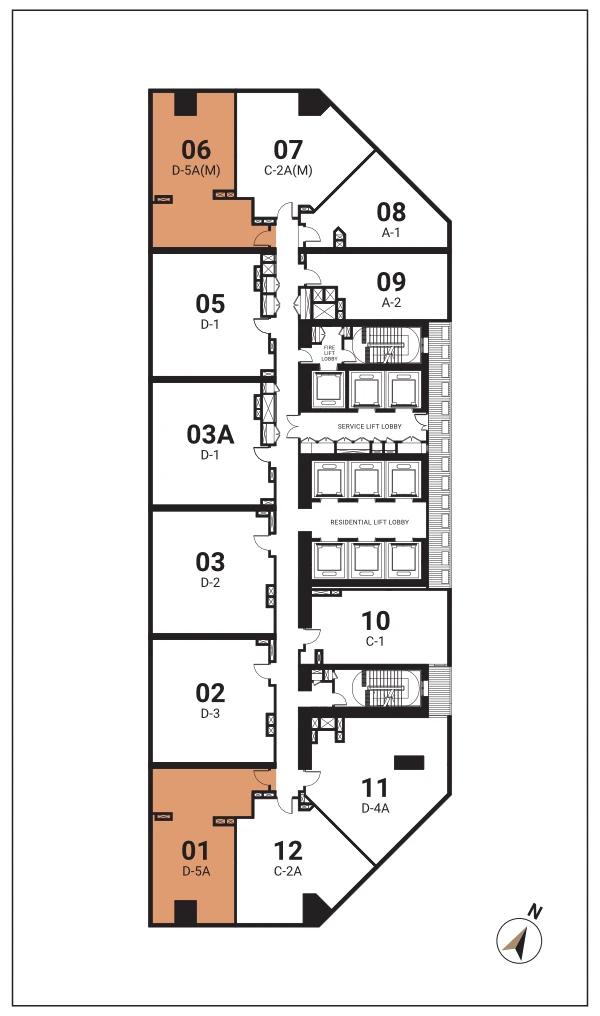
Type D-5A — 894 sq ft
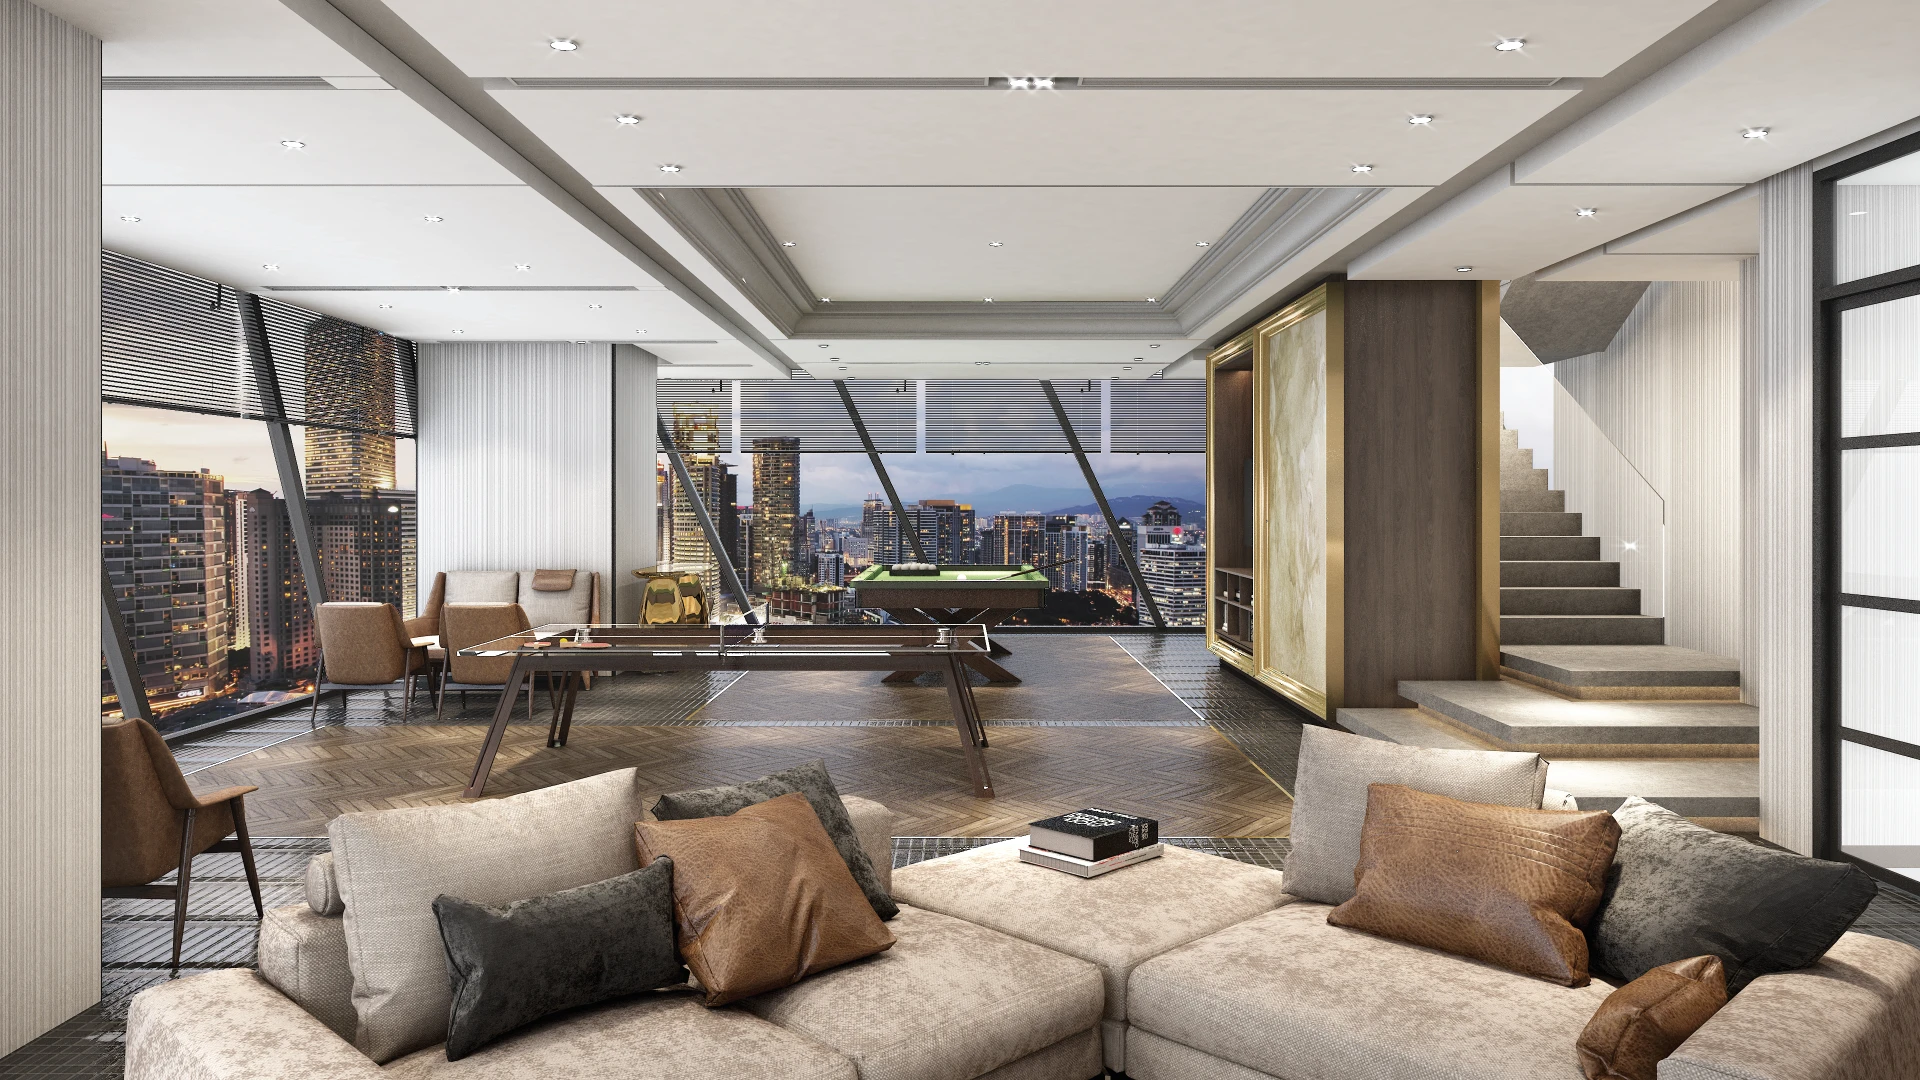
Get this floor planInside SO/ Kuala Lumpur Residences @ Oxley Towers KLCC
Where SO/ Kuala Lumpur Residences @ Oxley Towers KLCC sits
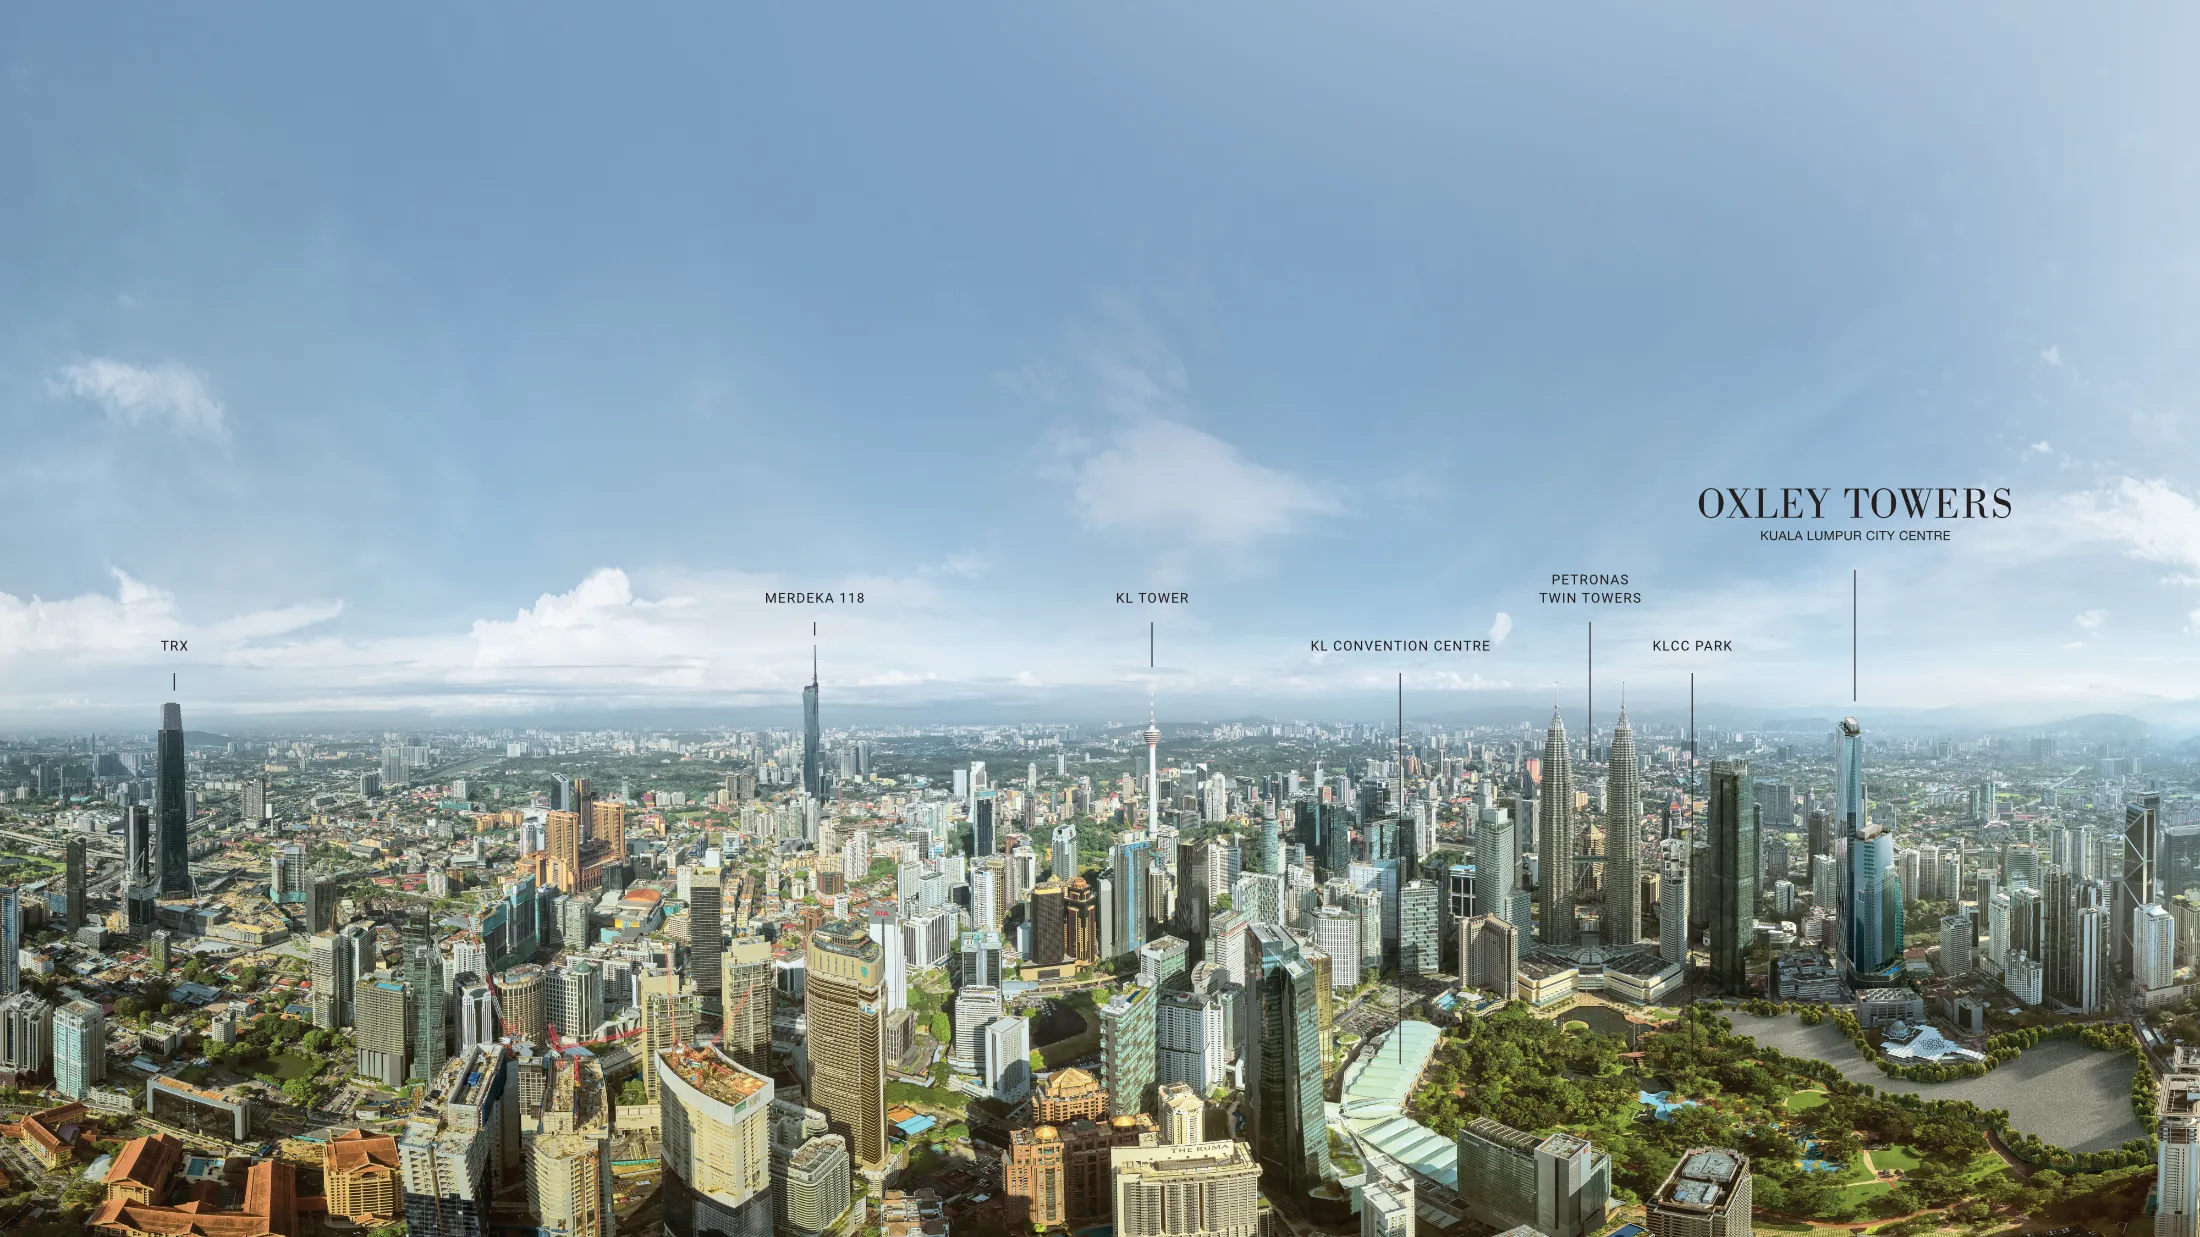
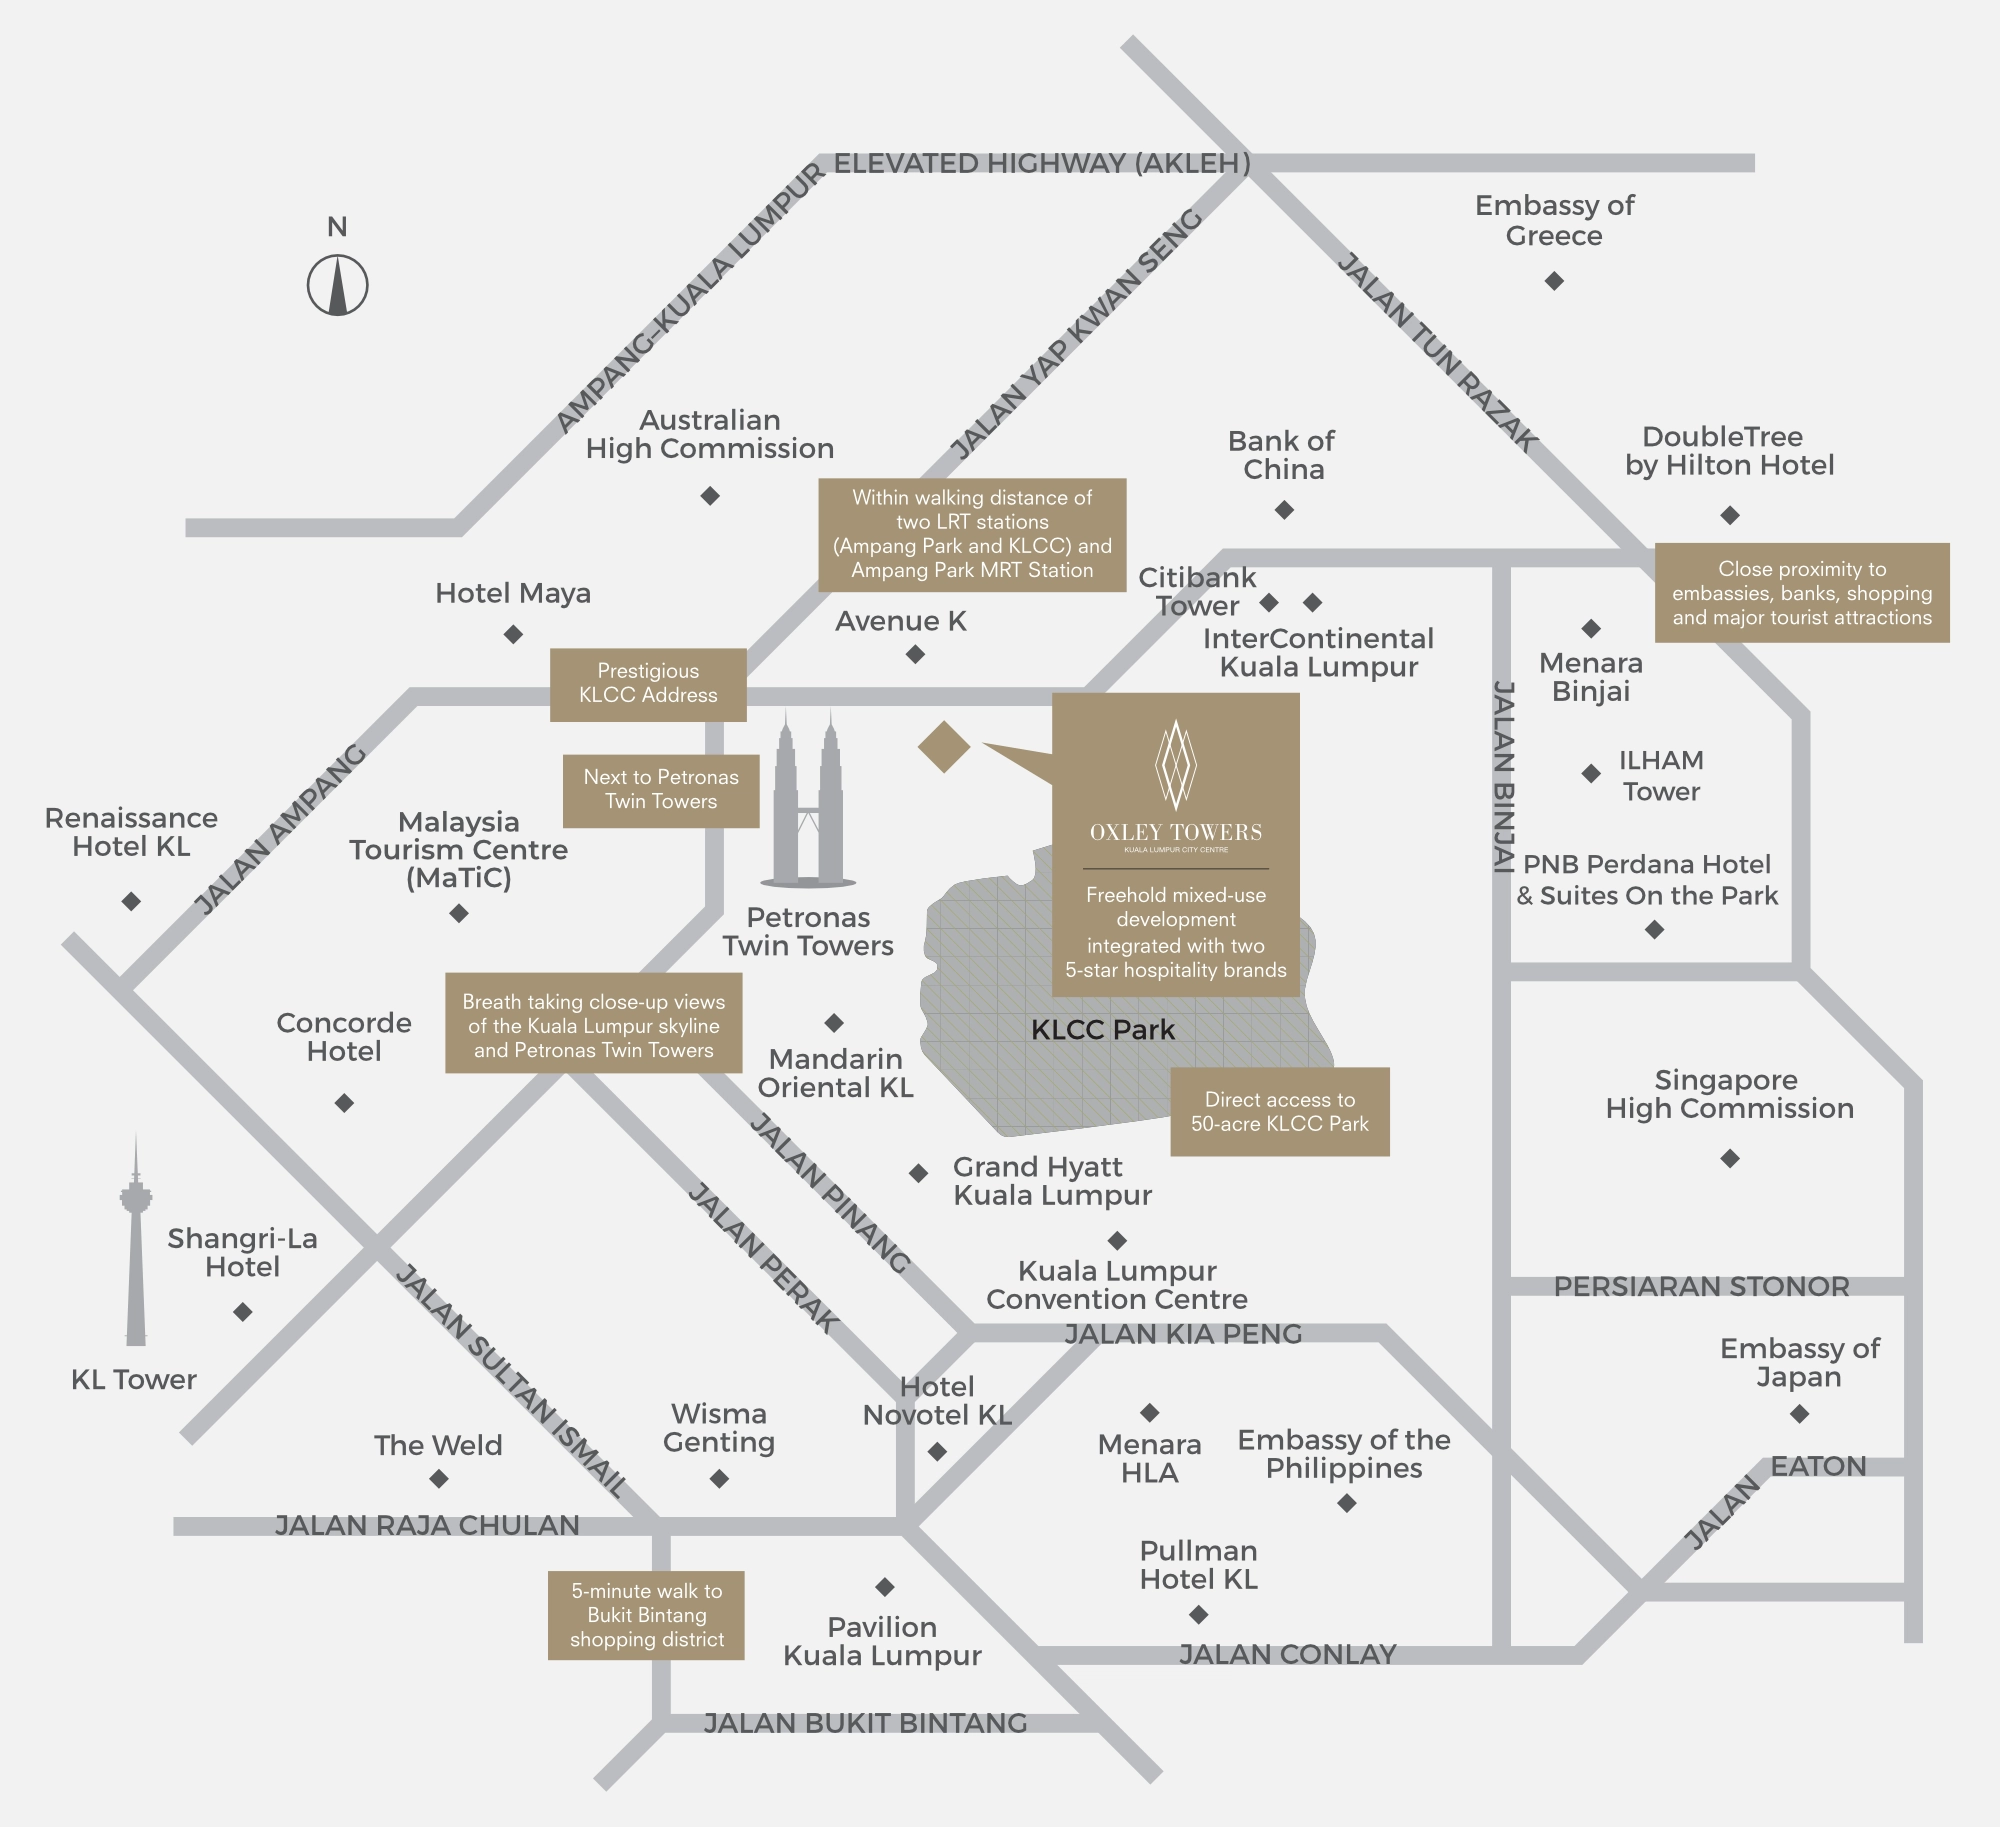
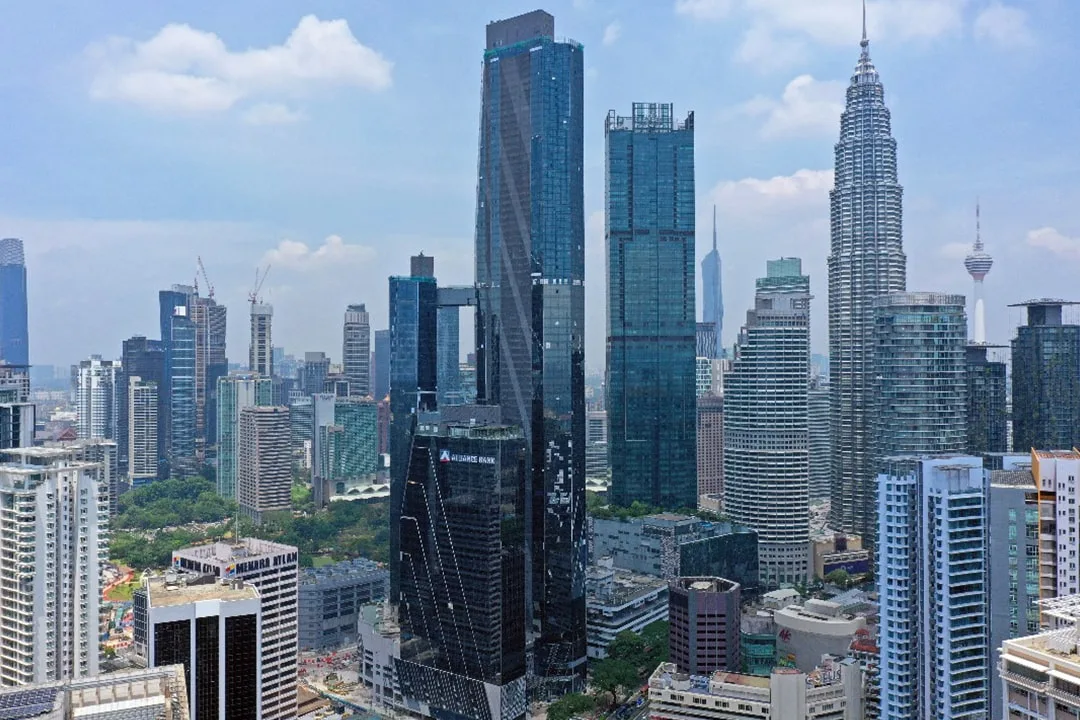
Jalan Ampang, Kuala Lumpur City Centre, 50450 Kuala Lumpur — a three-tower scheme of about 3.10 acres carrying the SO/ Kuala Lumpur Hotel and Residences, The Langham Kuala Lumpur with Jewel Residences, an office tower and a retail podium linking all three. Sales gallery: G-05, Aras G, Menara Oxley, No. 159 Jalan Ampang, 50450 Kuala Lumpur.
The developer publishes no coordinate for this building. Not a latitude, not a longitude, not a plus code, and not a street number for the tower itself. The only street address Oxley publishes on this project is its sales gallery at G-05, Aras G, Menara Oxley, No. 159 Jalan Ampang, and a sales gallery is not the block you would be buying into. The map above is therefore set by a place query on the scheme name and the road, not by a surveyed point, and it should be read as “this stretch of Jalan Ampang” rather than “this lift lobby”. Before you sign anything, ask for the lot and section numbers on the transfer documents and for the strata plan of your specific unit — those two documents locate your property in law, which a map pin never does.
- KLCC Park, 50 acres400 mthe developer’s own marketing claim — “400M TO 50-ACRE KLCC PARK”; not a measurement I have taken
- KL Sentral transport hub8 minutes by carthe developer’s claim, and note it is a drive time, not a distance — no traffic condition is stated
- Petronas Twin TowersNot verifieda “250 m from the Petronas Twin Towers” claim circulates widely, but it comes from oxleytowersklcc.com — an agency site, not the developer’s. Oxley itself publishes no figure. Treat 250 m as unverified until someone shows you a measured source
- LRT and MRT stationsNot publishedthe claim of “walking distance to 2 LRT and 2 MRT stations” also comes only from the agency site oxleytowersklcc.com. The developer names no station and publishes no distance to any station
- Retail podium inside the schemeIn the podiumpart of the development itself, linking all three towers; fully sold and to be managed by Pavilion Group
- Kuala Lumpur International AirportNot publishedOxley publishes no distance and no travel time to the airport for this project
- International schoolsNot publishedno school is named and no distance given in the developer’s material — a real gap if you are buying for a family, and one I would rather flag than fill with a guess
- Hospitals and medical centresNot publishednot named on the developer’s official location map material available to me
- Oxley sales gallery, Menara OxleySame roadG-05, Aras G, Menara Oxley, No. 159 Jalan Ampang — the only street address Oxley publishes for this project, and it is the gallery, not the tower
The statutory name is Menara Oxley, and the permitted band tops out at RM18.6 million
| Project code | Registered name | Licensed developer | Advertising permit | Units | Built-up | Price band on the permit | Built | Status |
|---|---|---|---|---|---|---|---|---|
| 19325-1 | Menara Oxley | Oxley Rising Sdn Bhd (19325) | 19325-1/02-2026/0028(R)-(S) | 857 | up to 84 sq m (about 904 sq ft) | RM1,378,000 – RM18,571,589 | 100% | Siap Dengan CCC |
Swipe sideways to see the full table →
Read from teduh.kpkt.gov.my on 27 August 2026. Pull it yourself: teduh.kpkt.gov.my/semakan-status-kemajuan?kodProjek=19325-1
Read the price band next to the floor area
The register records units up to about 904 sq ft, permitted at up to RM18,571,589. A thirteen-to-one band on floor areas that size tells you the pricing here was driven by floor, view and the branded-residence premium — not by square footage.
For a resale comparison, treat the band as the outer frame and nothing else. Ask for the last transacted prices in the building and compare against the specific stack and floor. A price per square foot averaged over “Oxley Towers” is not a usable number.
Foreign buyers
The bottom of the permitted band, RM1,378,000, already clears Kuala Lumpur’s RM1,000,000 minimum for a non-citizen buyer. Eligibility is not the constraint here.
Completed, so the questions change
Siap Dengan CCC means the Certificate of Completion and Compliance has been issued and construction is recorded at 100%. On a branded serviced residence the questions that move value are different from an ordinary condominium: what the hotel-operator agreement costs the management corporation, what the maintenance charge and sinking fund are per square foot, what the latest audited management account shows, and what happens to the branding if the operator agreement is not renewed. None of that is on a government register — ask the management office for the last audited accounts and the operator agreement term.
About Oxley Rising Sdn Bhd (Oxley Holdings Limited)
The entity that develops and sells this project — and therefore the entity your sale and purchase agreement names — is Oxley Rising Sdn Bhd, Company No. 1053340-P, registered at Upper Penthouse, Wisma RKT, No. 2, Jalan Raja Abdullah off Jalan Sultan Ismail, 50300 Kuala Lumpur. Above it sits the Malaysian holding company, Oxley Holdings (Malaysia) Sdn Bhd (1048417-1), and above that the listed parent, Oxley Holdings Limited, Singapore Registration No. 201005612G, quoted on the Main Board of the Singapore Exchange. Two jurisdictions, two sets of obligations: the Singapore company files the results you can read, the Malaysian company signs the contract you can enforce. When something goes wrong, those are not the same counterparty, and it is worth knowing which name is printed on the document in front of you.
The listed parent’s most recent full-year figures are the ones to read. For FY2025, the year to 30 June 2025, Oxley Holdings reported a profit before tax of S$3.6 million, against a loss before tax of S$106.1 million the year before — a swing the group attributed mainly to construction completion at Tower 1 of Oxley Towers KLCC. That is this building. On the balance sheet, bank borrowings and fixed rate notes stood at S$1,243 million, of which S$1,155 million was secured; S$88.0 million of unsecured fixed rate notes were fully redeemed after year end; the group deleveraged by S$126.2 million during the year and finance costs fell 21%. Total equity was S$854.4 million and net asset value 19.60 Singapore cents per share.
Then, on 29 July 2026, the parent issued a profit warning. Its words: “the Group is expected to report a loss after taxation for FY2026, notwithstanding achieving a profit after taxation for the first half year ended 31 December 2025.” The causes given were fair value adjustments and impairment losses, and the group said it “expects to recognise an impairment loss in respect of the development property” — the development property being the Oxley Towers KLCC luxury hotel. FY2026 results are due on or before 29 August 2026 and had not been published as at 11 August 2026, the day this page was verified. Here is the distinction that actually protects you: this is a profit warning plus asset impairments, not a going-concern warning. The FY2025 audit opinion was clean and unqualified, with no going-concern paragraph in it. Writing down the carrying value of a hotel is an accounting event about one asset. A going-concern qualification is an auditor questioning whether the company survives the next twelve months. Anyone describing this as the second thing is either careless or selling you something.
The last piece is the hotel strategy, because it changes what the branded part of this address is worth. On 29 July 2026 the group completed the sale of a 30% interest in the luxury hotel for RM250 million. Read the detail carefully: the hotel in that transaction is owned by Artisan Hospitality Sdn Bhd, held 70% by Oxley Rising and 30% by Kindway Express Limited, and “will be managed under the Langham brand”. That is Tower 2. It is not the SO/ hotel underneath these residences, and it is widely reported as though it were. Separately, the group has stated it intends to divest the hotel business when the opportunity arises. Neither hotel is open — the first is targeted to begin operations by Q4 2026. So the operator sitting under your building is, on the developer’s own stated plan, an asset for sale.
Frequently asked questions
What does the Accor SO/ brand licence actually give me as an owner?
Start with the sentence the developer publishes itself, printed beneath the Accor branding on its own site: “SO/ Kuala Lumpur Residences is not owned, developed or sold by Accor or its affiliates. Oxley Rising Sdn. Bhd., a company organised under the laws of Malaysia, is independently owned and operated and is solely responsible for the ownership, development, and operation of this Project herein.”
Read it precisely, because it is more interesting than the summaries of it. It does not say Accor “does not operate” the residences. It says Oxley Rising is solely responsible for the ownership, development and operation of the project. The practical effect is that Accor has no operational role in the residences. But it is a brand-licence carve-out, drafted to limit Accor’s liability — it tells you what Accor is not responsible for, and it never describes what Accor’s contractual role positively is.
So what have you actually bought? A residential flat in a tower that carries a hotel brand at its base, with a name licence attached. What you have not bought, unless a separate signed document says otherwise, is a hotel service contract. The developer markets 24-hour access to concierge and premium brands, and that is its marketing wording — the scope, the hours, the charges and the term are not published anywhere I can find.
There is no rental pool, no guaranteed return, no assured yield and no serviced-residence management scheme mentioned in any official source on this project. Not one. If a salesperson describes any of those to you, ask for the clause number in the sale and purchase agreement or the management agreement. If they cannot point to it, it does not exist.
Before you sign, get three things in writing: the exact services included with the residences, who provides them, and what they cost per month. A brand name on the door is not a service level agreement.
Can foreigners and Singaporeans buy here, and what does it actually cost in tax?
Yes, you can buy — here is what to watch. Kuala Lumpur applies a minimum purchase price of RM1,000,000 to foreign interests, and “foreign interest” is defined to include Malaysian permanent residents. On this project that threshold is unlikely to bite: the developer’s own bulk deal implies about RM2.22 million a unit. But the test is applied to the price of your transaction, not to a launch list, so fix the number before you negotiate.
Consent comes next. A transfer to a non-citizen requires written state consent under section 433B of the National Land Code. In the Federal Territory it is granted by the Federal Territory of Kuala Lumpur Land Working Committee (Jawatankuasa Kerja Tanah Wilayah Persekutuan Kuala Lumpur) and applied for through the Federal Territory Land and Mines Office after the sale and purchase agreement is signed. It is not the EPU, whatever an old article tells you, and it is the Land Working Committee. Build the application time into your completion schedule.
Now the money. From 1 January 2026 a non-citizen buying residential property pays a flat 8% stamp duty on the transfer instrument — no tiering, no first-home relief — and the Finance Act 2025 expressly lists service apartments and SOHOs as residential. At about RM2.22 million, that is RM177,600 payable in cash at transfer. On the way out, Real Property Gains Tax for non-citizens and foreign companies is 30% within five years and 10% from the sixth year onward, with no zero-rate band ever. Put both together and, to get your stamp duty back before year five, you need roughly RM253,700 of gain, about 11.4% on price. After year five, about RM197,300.
Financing: expect a loan margin of 60% to 70%. On RM2.22 million that is RM666,000 to RM888,000 of equity, plus the RM177,600 duty — call it RM843,600 to RM1,065,600 in cash, before legal fees and consent costs. And because this building is finished, the balance is not staged over a construction period; it falls due on the conveyancing timetable.
I am a property agent, not a tax adviser. Take these figures to a Malaysian tax professional and your own lawyer before you commit — but go in knowing the shape of the number, because too many buyers only discover the 8% line at the transfer stage.
I have seen “566 to 5,059 sq ft” quoted for this project. Is that right?
No. That range circulates widely and it is not supported by anything the developer publishes. Oxley publishes exactly nine layouts for SO/ Kuala Lumpur Residences, and they span 566 to 995 sq ft — A-2 at 566 sq ft is the smallest and D-4A at 995 sq ft is the largest. That is the whole published range.
There is no published 5,059 sq ft layout. There is no published penthouse plan at all. All nine drawings sit on a single sheet headed TYPICAL FLOOR LAYOUT LEVEL 34-43 / 47-51, and nothing above or below that band has a plan in the public material.
Why does it matter? Because a size range is how buyers calibrate a whole project in their head. If you believe there are 5,000 sq ft units, you assume a tier of large family residences and price the building accordingly. In reality every published layout here is a studio, a one-plus-one, a dual key or a two-bedroom under 1,000 sq ft. That is a compact-unit building with a hotel underneath, which is a different investment thesis entirely.
If someone is genuinely offering you a unit outside 566 to 995 sq ft, that is not automatically false — a large combined unit or an unpublished layout can exist. But ask for the drawing and the strata plan for that unit specifically, in writing, before you pay anything. Do not accept a size range copied from a listing portal as evidence.
Is the project 75% sold or 58% sold?
Use 58%. The FY2025 annual report states the scheme was 58% sold as at 15 September 2025. The 75% figure comes from a press release dated 2 June 2025, which said the 100-unit bulk sales arrangement had “propelled overall residential sales… to an impressive 75%”.
The order of the dates is what makes this awkward. The 75% claim came first, in June. The 58% figure came three months later, in September, in an audited annual report — and it is lower. Sales percentages are not supposed to go backwards. Something was counted differently, or a booking did not convert, or the two numbers cover different denominators. The developer has not explained the gap, and I am not going to invent an explanation for it.
I use 58% for three reasons. It is more recent. It comes from an annual report rather than a marketing release. And when two of a company’s own numbers conflict, the conservative one is the one you should plan against.
The practical consequence is in the next answer but it is worth stating here: at 58% sold, roughly 42% of the scheme was still unsold as at September 2025, with about RM550 million of premium inventory retained by the group. That is the market you would be reselling into.
When someone quotes you a sales percentage on any project, ask for the date and the source document. A number without a date is not information.
Does it matter that the SO/ hotel will not open until Q4 2026 at the earliest?
It matters more than most people allow for, because the hotel is what the brand premium is built on. As at the FY2025 annual report both hotels on the site were still in final fit-out and renovation, and the first hotel is targeted to begin operations by Q4 2026. A target date published by a developer whose own website has not been updated since May 2025 is not a date you should build a rental plan around.
Think about what an unopened hotel means day to day. No hotel lobby activity, no food and beverage in the base of your building, no hotel staffing presence, and no operating concierge desk of the kind the marketing describes. The address works as a residential address in KLCC, which is a genuinely good thing, but the branded-living experience is a promise that has not commenced.
There is a second layer. The group has stated it intends to divest the hotel business when the opportunity arises. So the operator beneath you is, on the developer’s own stated plan, an asset for sale — and a new owner may or may not keep the same brand arrangement, the same standard or the same service offer. Nothing in the public material guarantees the brand stays for any particular period.
None of this is a reason to walk away. It is a reason not to pay a premium today for something that is not there yet. Price the flat as a completed freehold KLCC residence with a good address, and treat a functioning hotel underneath as upside that may or may not arrive on schedule.
If a seller is pricing in the brand, ask them to show you the document that ties the brand to the building for a defined term. Then decide what that document is worth.
Is the Langham 198 keys or 213 — and was the RM250 million sale the SO/ hotel?
The sale was not the SO/ hotel. This is the single most misreported fact about this development, so read it slowly. On 29 July 2026 Oxley completed the sale of a 30% interest in the luxury hotel for RM250 million. That hotel is owned by Artisan Hospitality Sdn Bhd, held 70% by Oxley Rising and 30% by Kindway Express Limited, and the announcement says it “will be managed under the Langham brand”. The Langham is in Tower 2. The SO/ hotel — the one under these residences, in Tower 1 — was not the subject of that transaction.
On the key count, Oxley contradicts itself. The official project website says “THE LANGHAM, KUALA LUMPUR — 198-KEY LUXURY HOTEL”. The FY2025 annual report says 213-room, and says it twice. I go with 213: the annual report is the more authoritative document and the more recent one, and the project website has not been updated since around April or May 2025.
Does a 15-key difference matter to you as a residential buyer in the other tower? Directly, no. Indirectly, yes — because it is another example of the same pattern running through this project. The office tower has three official storey counts. The sales percentage has two versions. The key count has two. When a developer’s own documents disagree this often, the correct response is not cynicism, it is discipline: take every figure from the most authoritative source, date it, and verify anything that will affect your money.
One thing the RM250 million sale does tell you is that a third party was willing to put real money into a hotel on this site at that valuation, which is a genuine data point about the scheme. Read it alongside the impairment the group flagged on the development property in the same announcement cycle, and hold both facts at once.
Oxley issued a profit warning. Should that worry me if my unit is already completed and handed over?
First, be precise about what it is. On 29 July 2026 the parent said “the Group is expected to report a loss after taxation for FY2026, notwithstanding achieving a profit after taxation for the first half year ended 31 December 2025”, citing fair value adjustments and impairment losses, and adding that it “expects to recognise an impairment loss in respect of the development property” — the Oxley Towers KLCC luxury hotel. FY2026 results are due on or before 29 August 2026 and had not been published as at 11 August 2026.
This is not a going-concern warning. That distinction protects you, so hold on to it. The FY2025 audit opinion was clean and unqualified, with no going-concern paragraph. An impairment writes down the carrying value of a specific asset in the accounts; a going-concern qualification is an auditor publicly doubting whether the company can continue trading. They are different documents saying different things, and conflating them is how people talk themselves out of, or into, decisions for the wrong reasons.
Now the part that actually applies to you. If a unit is completed and vacant possession has been given, the developer’s main obligations to that buyer have largely been discharged. What can still touch you is narrower: the defect liability period and whether the developer honours it, the handover of the management function to a management corporation, whether the promised common property and facilities are finished to specification, and the strata title issuance in due course. Those are the things a weaker developer balance sheet can slow down — and those are the things to ask about specifically.
There is also the market effect described elsewhere on this page. A group under pressure to convert inventory to cash has an incentive to move its remaining RM550 million of premium stock, and its discounting sets the price ceiling you would resell into. That is a more immediate risk to your money than the accounting headline.
Read the FY2025 figures for balance: profit before tax of S$3.6 million against a S$106.1 million loss the year before, S$1,243 million of borrowings and fixed rate notes with S$1,155 million secured, S$88.0 million of unsecured notes fully redeemed after year end, S$126.2 million deleveraged during the year, finance costs down 21%, total equity S$854.4 million, NAV 19.60 Singapore cents per share. Then wait for the FY2026 numbers and read them yourself rather than the headline about them.
If I let it out, who am I competing with and what is the honest picture?
Your first competitor is the developer, and that is unusual in a completed building. The scheme was 58% sold as at 15 September 2025, so roughly 42% remained unsold, and about RM550 million of premium inventory was being retained as at August 2025 with a stated aim of selling it within the following 6 to 12 months. A developer clearing inventory can rebate, absorb legal fees, furnish a unit, bundle parking or simply cut the price across a block. A private landlord competing on rent sits underneath whatever that campaign does to sentiment and to comparable values.
Your second competitor is the rest of the city. NAPIC’s figures for Kuala Lumpur in the first quarter of 2026 record 3,733 units of residential overhang and 4,181 unsold completed serviced apartment units. Completed and unsold stock in the same city is exactly what caps achievable rent, and it does not clear quickly.
What is genuinely in your favour is specific rather than general: a freehold title, a finished building you can inspect, a KLCC address on Jalan Ampang, compact efficient layouts from 566 to 995 sq ft that suit a single professional or a couple, and a retail podium in the scheme itself that is fully sold and to be managed by Pavilion Group. Those are things a tenant responds to.
What I will not give you is a yield. There is no rental pool, no guaranteed return and no management scheme published for this project by anyone official, so any projected return you are shown has been made up by whoever is showing it to you. Ask them for the source. Then ask them what their number does when the developer discounts the remaining 42%.
The honest way to build a rental case here is bottom-up: your actual purchase price, your actual financing cost at a 60% to 70% margin, the actual maintenance charge once you have it in writing, and the actual achieved rents on comparable units in the building. Send me the unit and I will assemble those four inputs with you rather than hand you a percentage.
Of the four Kuala Lumpur projects on this site, which one should I look at?
They are four different answers to four different questions, so start with your own question. Here is the honest split.
SO/ Kuala Lumpur Residences is the finished one. Construction completed in August 2025, first handovers in September 2025, freehold, 590 units in nine published layouts from 566 to 995 sq ft. You can walk it, inspect the finishes, meet the management office and measure your own unit today. The trade-offs are on this page: the scheme was 58% sold as at September 2025 with about RM550 million of premium inventory retained, so you compete with the developer on resale, and the SO/ hotel underneath is not open until Q4 2026 at the earliest. Choose it if you want a completed freehold KLCC address and you want to inspect before you pay.
Conlay by E&O is the largest and the most expensive. Freehold, 491 units, from RM1.46 million, with a parent listed on Bursa Malaysia. It is the strongest developer covenant of the four. But its published advertising permit expired in 2022 and the permitted completion date on that permit has passed — which is a documentation question you must have answered in writing before you commit. Choose it if the developer’s standing matters most to you and you are prepared to do that paperwork properly.
Victory Suites, The Face II, is the cheapest entry. From RM1,081,000, completed in 2022 and still selling, with a 327-room hotel operating inside the same tower. It clears the RM1 million foreign-buyer floor by a small margin, which is a real thing to watch if you negotiate. Choose it if the entry price is the binding constraint — but understand you are buying into a building with a live hotel operation in it.
Royal Lexis Kuala Lumpur is the one nobody can evaluate yet. No price, no permit, no completion date and no unit count has been published. That is not an accusation, it is simply an absence of information — and it means any comparison you make with it is guesswork. Watch it; do not commit to it on what is currently public.
If you want a short version: inspectable and finished, take SO/. Developer strength above all, take Conlay and resolve the permit question. Lowest entry, take Victory Suites. Royal Lexis is a watch, not a buy. Tell me your budget, your nationality and whether this is to live in or to let, and I will narrow it to one.
Send me the unit number and I will price the whole transaction, not just the unit
This building is finished, so the questions that decide your outcome are arithmetic ones: what the 8% stamp duty adds on the way in, how much cash you need at a 60% to 70% loan margin when the whole balance is due at once, what the developer is currently discounting the remaining stock by, and what the last comparable resale actually closed at. Give me the stack and the size and I will put those four numbers next to each other before anyone talks about a deposit.
No agent fee payable by the buyer on new developer launches
Louis Koh
11 years in Malaysian property · Johor Bahru & Kuala Lumpur new launches · English & 中文
I work with cross-border buyers from Singapore and with local investors. I'll tell you when a project isn't right for you — that's usually worth more than the brochure.
Published 2026-08-11 · Last verified 2026-08-11 against Oxley Rising Sdn Bhd (Oxley Holdings Limited)'s published project material. Unit availability, pricing and completion dates are set by the developer and subject to change. This page is marketing information, not an offer or a contract.
Worth putting beside this one
Ask a specific question
If you would rather not use WhatsApp, use this. I answer them myself. Only your name and one contact method are required.
Developer: Oxley Holdings (1 development on this site)
Where it is: KLCC, Kuala Lumpur (KL)
The unit mix, the permitted price and how far up it is
None of this table is the developer’s account of itself. It is what the Ministry of Housing and Local Government records from the 7(f) returns: unit type, bedrooms and bathrooms, built-up area, unit count, the price range on the permit, and the certified percentage complete. A brochure price can be revised; the price on the permit was filed. A brochure need not mention progress; the percentage is certified. The status vocabulary is theirs too: Lancar (on schedule), Lewat (behind), Sakit (sick), Terbengkalai (abandoned).
19325-1 · MENARA OXLEY
Overall status: Siap Dengan CCC — completed
| Component | Bed / bath | Built-up | Units | Price on the permit | Complete |
|---|---|---|---|---|---|
| Pangsapuri Servis 54 storeys Siap Dengan CCC | 1, 2, 3 / 1, 2, 3 | 0 – 84 m² | 590 | RM1,378,000.00 – RM18,571,589.00 | 100.00% |
| Pangsapuri Servis 25 storeys Siap Dengan CCC | 1, 2, 3 / 1, 2, 3 | — | 267 | RM1,572,000.00 – RM3,400,000.00 | 100.00% |
Swipe the table sideways for the rest of the columns.
This is the document the developer had to file, and the housing department had to approve, before it was allowed to advertise at all — served from the ministry’s own host. It normally carries the location plan, the developer licence and building-plan approval references, the expected completion date, the encumbrance position, and the unit count and price floor and ceiling for each type. The brochure a salesperson hands you can be reissued. This one cannot.
Read from teduh.kpkt.gov.my on 2026-10-17, project code 19325-1. Re-read weekly.
What to do with the number. Read it against the delivery date in your own agreement, not against what a salesperson says. A project with a year left on its statutory clock and a third of the building up is telling you something the brochure will not.
How does that compare? Every development on this site, grouped by register status — cancelled, abandoned and behind schedule first.